
Quick Answer
Accept credit cards when the supported checkout and customer benefit justify their all-in cost. Compare product-specific fees, settlement timing and dispute exposure with an available bank route. Agree methods and any lawful price treatment before billing. Test in the provider’s sandbox, then reconcile genuine customer payments through fees, reserves and payouts; a delayed payout is not a reason to charge the client again.
Set your payment rails before work starts#
Card acceptance can be useful when clients prefer it and the expected collection benefit justifies the cost. Decide from your invoice size, supported market, payment mix and cash needs; neither cards nor bank transfers are automatically the right default.
Before work starts, decide which payment methods you support and how they appear in the proposal, contract and invoice. Check both the customer’s payment experience and your settlement, fee and dispute exposure. An easier checkout can help a client act, but it does not guarantee payment or immediate usable cash.
Use a simple lens on every invoice:
- Gross invoice amount
- Payment method and payment terms
- Net cash that lands in your business bank account
That order prevents a common mistake. Many freelancers optimize for a paid status in a dashboard, then realize too late that fees, timing, or disputes changed the real outcome. Net cash is what matters for payroll, software, tax set-asides, and your own pay.
Your payment policy also needs to be repeatable. If you have to reinterpret terms every time you bill, clients will too. Consistency protects the relationship when something goes wrong because both sides can point to the same rule and the same document trail.
It also makes client conversations easier. Instead of debating mechanics in the middle of a project, you can explain one policy: this is the default rail, this is the fallback, this is how timing works, and this is what happens if payment fails or gets challenged. Clear language early removes most payment drama later.
The failure mode to avoid is ad hoc switching. If you change payment rails case by case without updating documents, your proposal says one thing, the contract implies another, and the invoice asks for a third. That mismatch usually shows up when money is already due, which is the worst time to negotiate rules.
Before anything goes live, run one last checkpoint. Confirm that payment terms match across the proposal, contract, and invoice, and confirm that your default and fallback methods are described the same way in all three. If you want the simplest setup, choose one primary method at kickoff and reserve the other for exceptions. If you want to tighten the wording quickly, try the free invoice generator.
Once that policy is set, look at what card acceptance actually changes in your cashflow.
What accepting credit cards changes in your cashflow#
A successful card payment and an available bank payout are separate events. Track the captured amount, pending/available balance, processor adjustments and bank deposit. Even paid-out funds can later face a refund or dispute; payout is not immunity from reversal.
| Provider | Transaction example | Listed pricing |
|---|---|---|
| PayPal U.S. Invoicing, domestic USD | Standard cards / Apple Pay / third-party wallets | 2.99% + $0.49 |
| PayPal U.S. Invoicing, domestic USD | PayPal Checkout / Venmo / Guest Checkout | 3.49% + $0.49 |
| PayPal U.S. Invoicing, domestic USD | Pay Later | 4.99% + $0.49 |
| Stripe Mexico, standard online | Domestic cards | 3.6% + MXN3.00, excluding VAT |
| Stripe Mexico, standard online | International-card add-on | +0.5 percentage points |
| Stripe Mexico, standard online | Required currency-conversion add-on | +2 percentage points |
Use this order every time: gross amount, processing cost, dispute exposure, then net cash in bank. The sequence matters because it ties the decision to spendable cash, not platform activity. Paid in a portal is not the same as settled funds you can rely on for operating expenses.
The table uses provider pages checked October 5, 2026. PayPal rates depend on the product: a U.S. invoice card payment is not the same product as Advanced Card Payments. Stripe’s Mexico fees are a separate merchant-market example and exclude VAT. Add applicable tax on fees, invoicing/billing charges, FX, payout costs and later adjustments before estimating usable cash.
Worked fee examples before other adjustments: a $1,000 domestic USD PayPal invoice paid by standard card costs $30.39 at 2.99% + $0.49, leaving $969.61; PayPal Checkout at 3.49% + $0.49 costs $35.39, leaving $964.61. For a MXN10,000 Stripe Mexico online domestic-card charge, the stated fee is MXN363 before VAT. With both the international-card and required-conversion add-ons, it is MXN613 before VAT. These calculations exclude reserves, refunds and any additional product charges; compare like-for-like merchant markets.
In practice, this is where margin surprises happen. The work can stay exactly the same while the payment rail changes the economics. If you quote before classifying the likely transaction path, you can lock in a price that looked healthy until fee layers and settlement behavior were factored in.
For cards, identify the merchant account country and issuer/card country under the provider’s rules; the client’s office address alone does not determine domestic status. Identify payment and settlement currencies separately. A customer abroad may use a locally issued card, or a local customer may use a foreign card.
Treat disputes as normal operating risk, not as a rare edge case. PayPal merchant fee documentation includes sections for Dispute Fees and Chargeback Fees. You do not need to assume every client is risky, but your margin model should survive routine payment friction.
Use this short check before you enable card checkout for a client:
- Identify merchant country, card issuer country, product, payment currency and settlement currency.
- Estimate net cash after processing cost and potential dispute cost.
- Verify your current provider pricing page and policy updates.
- Match invoice wording to the method you are offering.
If the expected cost pushes the project outside your margin tolerance, route to bank transfer first and keep cards as a backup. Once you look at cards through net cash instead of dashboard status, the routing decision gets much easier.
Decide when to use cards and when to push bank transfer#
Use the method that fits the actual engagement. Bank transfers may have lower collection fees on a large invoice, while cards may make authorization easier for a particular client. Compare all-in cost, action required from the client, timing and recourse; bank payment can also be delayed, recalled or affected by fraud.
Do not leave that decision until after the invoice is sent. Late payment is common enough that collection rules belong at kickoff, alongside scope and timeline. By the time money is due, any ambiguity becomes leverage for delay.
Accepting a customer’s card payment is different from sending a payout to an eligible card. Push-to-card availability and delivery timing depend on the provider, network, recipient and transaction. Do not use a payout-network speed claim as a promise about when your card invoice will reach your bank.
Set a routing rule from the measured cost and client process. If cards make payment easier enough to justify the fee, offer them. If a bank route works for the client and has a better all-in result, offer that instead. Agree any later change in instructions rather than presenting a new fee or method after delivery.
Set a clear gate before project start:
- Estimate margin impact of card costs at the expected invoice size.
- Choose a primary payment method and a fallback before the first invoice.
- Keep terms aligned across proposal, contract, and invoice.
- If projected fees exceed acceptable margin loss, require bank transfer or reprice before kickoff.
If the choice is not obvious, offer both options in writing at the start and tighten the rule later based on actual payment behavior. That gives the client flexibility early without giving up your ability to protect margin once a pattern emerges.
After you know which rail should be primary, the next job is choosing tools that support that policy without adding unnecessary moving parts.
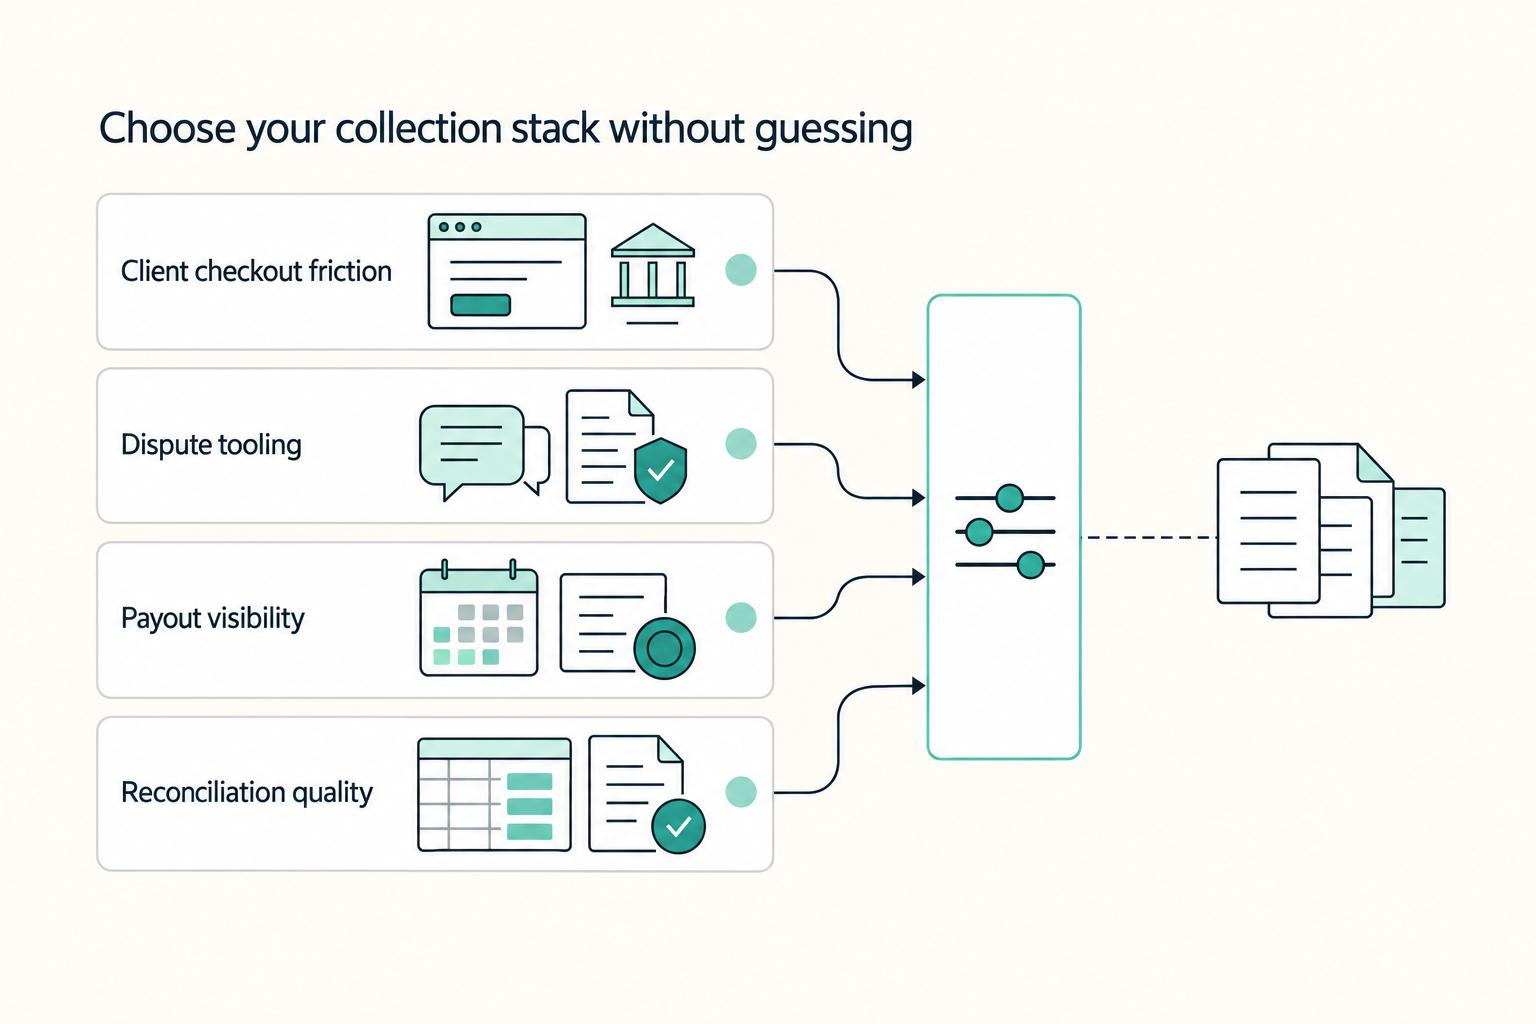
Choose your collection stack without guessing#
Separate the functions you need: invoice creation, reminders, hosted checkout, payment processing and payout reconciliation. One provider may bundle several; a gateway alone does not necessarily supply invoice management or the entire funds flow.
That separation matters when something goes wrong. If a client says they paid, a payout is delayed, or a dispute opens, you can isolate the issue quickly. Is it processor status, invoice configuration, or internal recordkeeping? Clean boundaries make that diagnosis faster.
| Criteria | Stripe | PayPal | Wise |
|---|---|---|---|
| Client checkout friction | Depends on your invoice and collection setup | Payment Links can be created quickly with no coding | Built for receiving bank transfers through account details |
| Dispute tooling | Disputes can be managed in the Dashboard or API | Resolution Center supports buyer and seller communication on disputes | This comparison focuses on transfer receiving, not card dispute handling |
| Payout visibility | Dashboard shows payouts; available schedules depend on account country and do not shorten settlement timing | Review visibility in your specific PayPal product flow before standardizing | Check supported holding/receiving currencies and actual statement fields for your account country |
| Reconciliation fields | Match invoice/payment IDs to balance transactions, fees and payout IDs | Match invoice and payment references to adjustments and transfers | Match account receipt references, conversion records and bank transfers |
Avoid stack creep. Every extra app can add another failure point, another export format, and another place where client records and finance records drift apart. Start lean, document ownership, and only add tools when a specific reporting or control gap is actually hurting operations.
Native invoicing may be enough for a small practice. Check reminder settings, payment methods, product charges and exports in the actual account. A separate layer can help with multi-provider billing; Billbooks lists reports and integrations with PayPal, Stripe, Braintree and Authorize.Net. Confirm availability, subscription cost and the gateway’s own processing fees before adding it.
Keep the business description, legal identity and processor profile accurate. Stripe uses the selected industry group to help determine the Merchant Category Code and evaluates the account for an appropriate code. If the description or code appears wrong, use support to correct it; do not select a misleading category to seek lower fees.
Then do a simple monthly review. Reconcile invoice totals to payouts, confirm that reminder behavior still matches your terms, and spot-check a recent client journey from invoice send to bank deposit. That routine catches drift before it becomes a collection problem.
Once the stack is stable, your documents need the same discipline. If cross-border collection is part of your model, How to Get Paid in Multiple Currencies Without Losing Your Shirt is a useful companion read.
Set payment terms that prevent disputes before they start#
Documentation does more to prevent disputes than payment method choice. When scope is fuzzy, approvals are undocumented, or timing is implied instead of stated, the invoice becomes the first place where misalignment gets exposed.
The fix is straightforward: set terms once, early, and repeat them with the same meaning across the proposal, contract, and invoice. At minimum, cover deposit policy, milestone triggers, revision limits, late payment language, and accepted methods. If billing depends on approval, define what counts as approval and where that approval is recorded.
Before you sign, pressure-test the language with one practical question: could someone outside your team read these terms and know exactly when payment is due and why? If not, tighten the wording now. The longer ambiguity survives, the harder it is to unwind later.
If card checkout is available, add a plain-language card clause. State how card payments are processed and which records both sides will rely on if a payment is challenged. Then mirror that logic in the invoice notes so every document tells the same story.
For each billed milestone, keep one evidence packet:
- Signed scope or signed change order
- Delivery proof tied to that milestone
- Client approval timestamp
- Final invoice version sent to the client
This turns payment friction into a records review instead of an argument about memory. It also shortens dispute handling because your proof is already organized before anyone asks for it. If you want to revisit tooling choices with this evidence standard in mind, The Best Invoicing Software for Freelancers can help you choose what to standardize.
Good terms still fail if the live invoice flow is sloppy, so the next step is getting the sequence right.
Build the invoice and checkout sequence in the right order#
Get the setup sequence wrong and you create your own payment delays. Reliable collection usually comes from sequence and verification, not from offering more payment options.
Complete processor onboarding, confirm supported payment methods and verify the payout account before enabling billing. Use the correct legal seller identity and any authorized trading-name treatment consistently. Account review and initial payout timing vary; confirmation that checkout is enabled does not prove that funds will immediately be available.
Keep payment instructions in two distinct invoice paths instead of one crowded block:
- Primary method: the route agreed for this invoice, with its exact instructions.
- Alternative method: a supported fallback, with any lawful price treatment disclosed and agreed in advance.
When you send the first live invoice, spell out the path in plain language near the payment block. Clients should not need to infer whether transfer is expected or card is optional. One clear sentence can prevent back-and-forth that slows payment by days.
Verify the invoice/checkout flow in the provider’s sandbox or test mode first. Test payments do not prove a live bank payout. Then reconcile the first genuine customer invoice through capture, fees, settlement and payout; do not create fictitious live card charges to test the setup.
- In sandbox/test mode, use a unique invoice reference and verify checkout, failure, authentication and invoice-paid behavior where supported.
- Keep test and live credentials/data separate; simulated payments do not move real funds.
- For the first genuine sale, match the customer’s captured payment to fees, pending availability and any reserve.
- Match the eventual bank payout to its processor reference and component transactions; investigate differences rather than billing the customer twice.
If the customer payment succeeded but payout is delayed, check pending availability, account review, reserve notices and bank details before contacting the client. Do not ask the client to pay again merely because your processor has not paid out. Keep their payment separate from your settlement exception.
This sequence also makes pricing conversations easier. When operational steps are clean, clients see stable instructions and consistent totals, which makes fee policy easier to explain and enforce.
Price for fees without surprising clients#
Fee policy should be settled before the quote leaves your desk. Clients can usually work with any reasonable model when it is clear up front. Friction starts when totals change at checkout.
A fee-inclusive quoted price is often simplest. If you offer a discount for bank payment or a card surcharge, confirm the law, card-network rules and processor agreement for that market and product before publishing it. Client consent and the label “convenience fee” alone do not make an otherwise prohibited surcharge permissible.
| Policy | Best fit | Tradeoff to manage |
|---|---|---|
| Fee-inclusive pricing | Retainers where predictable billing matters | Margin can tighten as card share rises |
| Separate card surcharge, where permitted | A market/product with lawful and processor-supported surcharging | Network/product limits, acquirer notice and checkout/receipt disclosures |
| Rail-based pricing with bank transfer discount | Higher-ticket or fee-sensitive work | Check lawful discount presentation; display the card price clearly and do not disguise a surcharge |
Wise’s Canada Business page checked October 5, 2026 advertises sending/conversion from 0.19%, varying by currency, and volume discounts above C$35,000 equivalent. Those are outbound/conversion terms, not a credit-card acceptance rate or a universal receiving fee. Quote receiving, conversion and sending separately for the actual account country and route.
Keep transaction types separate as well. Wise lists a 2% fee for topping up external e-wallets, so those should not be priced as if they were standard transfer receipts.
A short client script helps prevent last-minute friction: this is the baseline total, this is when card checkout applies, and this is how your final amount is determined. If that script does not match your invoice terms, pause and fix the wording before you send anything.
Before issuing an invoice, run this alignment check:
- Proposal and invoice use identical fee language and payment labels.
- Instructions clearly state when to use transfer versus card.
- Tax and line-item structure match the signed scope.
- File contains the approved quote version and final invoice copy.
Clear pricing removes surprises, but it does not replace operational discipline. That is why the next risk area is ownership, records, and exception handling.
Red flags that cause holds, disputes, and payment chaos#
Holds and disputes can occur despite complete records, sometimes without an obvious warning. Clear documentation helps you respond; it does not prevent every risk review, fraud event or reversal.
Unclear terms, weak delivery evidence and split ownership make exceptions harder to resolve. Keep the signed scope, client payment, settlement and dispute records together. A contract does not override the customer’s card-network rights, and an approval email does not guarantee a successful defense.
Ownership is the first control to tighten. A common failure mode is shared responsibility with no accountable owner. One person sends invoices, someone else replies to dispute notices, and nobody maintains a complete evidence packet. Assign one owner for payment exceptions so provider responses, client communication, and internal records stay aligned.
The early-warning signs are usually operational, not technical. Repeated requests for revised invoices, inconsistent payer names, missing approvals, or delayed responses on acceptance can all point to avoidable payment risk. Treat those signals as a prompt to tighten documentation before your next bill goes out.
Use this risk check for each new client:
- Entity name and payer identity match across contract, invoice profile, and payment method.
- Scope and acceptance criteria are signed before any deposit request.
- Invoice line items mirror approved scope with no surprise additions.
- Delivery proof is stored with timestamps and approver identity.
- One owner handles failed payout escalation and client communication.
Treat pay-to-play language as a hard pause. Legitimate freelance work should not require paying upfront just to participate, so stop and verify before you proceed.
Provider programs and market context can shift review behavior, payout timing, and fee treatment, including in the United States. Use provider terms as the source of truth. If disputes or evidence gaps start trending up, tighten scope approval and identity checks before the next invoice leaves your queue.
Make cards a controlled option, not your only option#
Use cards deliberately where they fit the client and economics. A supported bank alternative can be useful, but a mixed setup is not mandatory for every practice. Each offered route needs clear instructions, pricing and reconciliation.
Choose from actual quotes and outcomes, not an assumed ranking. Preserve the distinction between the client’s paid balance, your pending processor balance and bank cash. Fees, reserves, refunds and disputes can change those amounts at different times.
Cards can reduce waiting and help with some unpaid-invoice friction, but faster settlement is never guaranteed. Build decisions around what actually lands in the bank account, not around what a checkout status suggests should happen.
Lock terms before delivery begins. Agree on payment method and timing at kickoff, then mirror them across proposals, contracts, and invoices so accepted options, due dates, and handling rules stay aligned.
Use this monthly operating checklist:
- Set a primary method and fallback by client type.
- Confirm method and payment terms before kickoff.
- Re-test invoice flows after provider or template changes.
- Review disputes, payout delays, and holds each month.
- Keep complete evidence records for every invoice.
As your client mix changes, revisit routing rules, fee policy, and evidence standards together instead of adjusting each piece in isolation. That keeps the collection process coherent as volume grows and payment behavior shifts.
If your payment mix shifts, reassess with Stripe vs PayPal vs Wise for Freelancers in 2026. If you want a country-specific pass before rollout, talk to Gruv.
Frequently Asked Questions
Should freelancers accept credit cards or stick to bank transfers?
Offer the supported methods that suit your clients and costs. Cards can improve convenience; a bank route may cost less on a large invoice but still has timing and fraud risks. Decide from an actual quote and payment process, and agree the method and any lawful fee treatment before billing.
What is the easiest way to start accepting credit card payments as a freelancer?
Choose a provider available to your business, complete onboarding and payout verification, then test invoice and checkout behavior in its sandbox. Reconcile your first genuine sale to the bank payout. Do not use fabricated live card transactions as tests. Check local product charges; “no setup fee” does not mean no processing, invoicing or other fees.
Is Stripe or PayPal better for freelancers who invoice clients?
Neither wins universally. Compare the same merchant country, invoice product, payment type, currencies and invoice amount. Use the scoped fee table above, then assess reminders, customer checkout, settlement timing and dispute handling. A PayPal Advanced Card rate is not automatically the rate charged through PayPal Invoicing.
When should I route a client to bank transfer instead of card?
Offer bank transfer where its supported route and all-in cost fit the client and engagement better. Include any receiving, intermediary, conversion and administration costs. For cards, issuer country and settlement currency can add fees independently. Agree the choice before the invoice rather than demanding a switch after payment.
Should I pass credit card fees to clients or build fees into my rates?
Including fees in the quoted rate is often simpler. A separate surcharge or bank discount needs compliance with local law, network rules and processor terms—not just disclosure. For U.S. Visa, debit/prepaid cards cannot be surcharged; eligible credit-card surcharges are capped at the lower of the applicable merchant discount rate or 3%, with acquirer notice and disclosures. Check current rules for your case.
How do I reduce chargebacks when I accept card payments?
Keep signed scope, delivery proof, approval timestamps and the final invoice, and address complaints promptly. If a dispute opens, follow its provider deadline and submit evidence addressing the actual reason. Stripe permits one final evidence submission, without later additions. Accept or contest an open dispute through its process; do not issue an independent second refund for the same disputed payment. Records improve the response but do not guarantee a win.
Do I need both a payment gateway and invoicing software?
Not necessarily. Check which invoice, checkout, reminder, processing and export functions your provider actually includes and charges for. Add a separate invoicing layer only if it fills a defined need, such as multi-provider reconciliation. Keep invoice and payment IDs linked across the tools.
Watch
Should Freelancers Accept Credit Cards?
Try a related tool
Researched and edited by the Gruv editorial team. Gruv builds cross-border billing, payouts, and finance-operations software for global businesses.
Sources
Includes 1 external source outside the trusted-domain allowlist.
- docs.stripe.com/testingtrusted
- docs.stripe.com/payoutstrusted
- paypal.com/us/business/paypal-business-feestrusted
- paypal.com/us/cshelp/article/how-do-i-create-and-send-a...trusted
- stripe.com/mx/pricingtrusted
- support.stripe.com/questions/setting-an-industry-group-when-cre...trusted
- wise.com/ca/pricing/businesstrusted
- billbooks.comexternal
Educational content only. Not legal, tax, or financial advice.
Related Posts

Stripe vs PayPal vs Wise for Freelancers in 2026
Cashflow reliability matters more than brand familiarity. If money arrives later than expected, gets reduced by fees, or loses value during conversion, margin disappears even when the client technically paid on time.

The Best Invoicing Software for Freelancers in 2026
Choose invoicing software by billing reliability and your actual workflow. This guide groups tools into three lanes so you can shortlist, then run an end-to-end invoice test before migrating clients. For a broader workflow, pair it with [Automating Your Freelance Finances](/blog/automating-freelance-finances).
How to Get Paid in Multiple Currencies Without Forced FX
To get paid in multiple currencies, first check whether your account can receive and hold the client’s currency. Where that route is supported, separate receipt from conversion so you can choose when to convert for expenses or home-currency cash needs. Holding currency also exposes you to exchange-rate changes and the account’s protection and access terms.