
Quick Answer
Define the cap amount, fee base, measurement period and aggregate or per-claim treatment. Specify whether indemnities and defense costs fall inside it, use a separate limit or are excepted. Check enforceability under the governing law and align scope, insurance and dispute procedure before signing.
Understand the exposure before negotiating#
Read the liability limit and indemnity together with the scope, warranties and remedies. The useful question is how much you could owe, for which event, and who pays to handle a claim. A cap that looks finite in one section may be bypassed by a carve-out elsewhere.
A contract should do more than restate good intent. It should tell both sides what the scope is, how payment works, and who is responsible if something goes wrong. You are not aiming for perfect language on day one. You are aiming for language that stays clear under pressure.
If a client asks you to accept more exposure, assess whether you can bear or insure it before discussing a higher fee. More revenue does not make an unlimited obligation affordable.
If you want a stronger baseline before heavy redlining, review The Ironclad International Freelance Contract: 10 Clauses You Cannot Ignore. Then mirror that structure in your current draft.
Gather your contract inputs before you touch a clause#
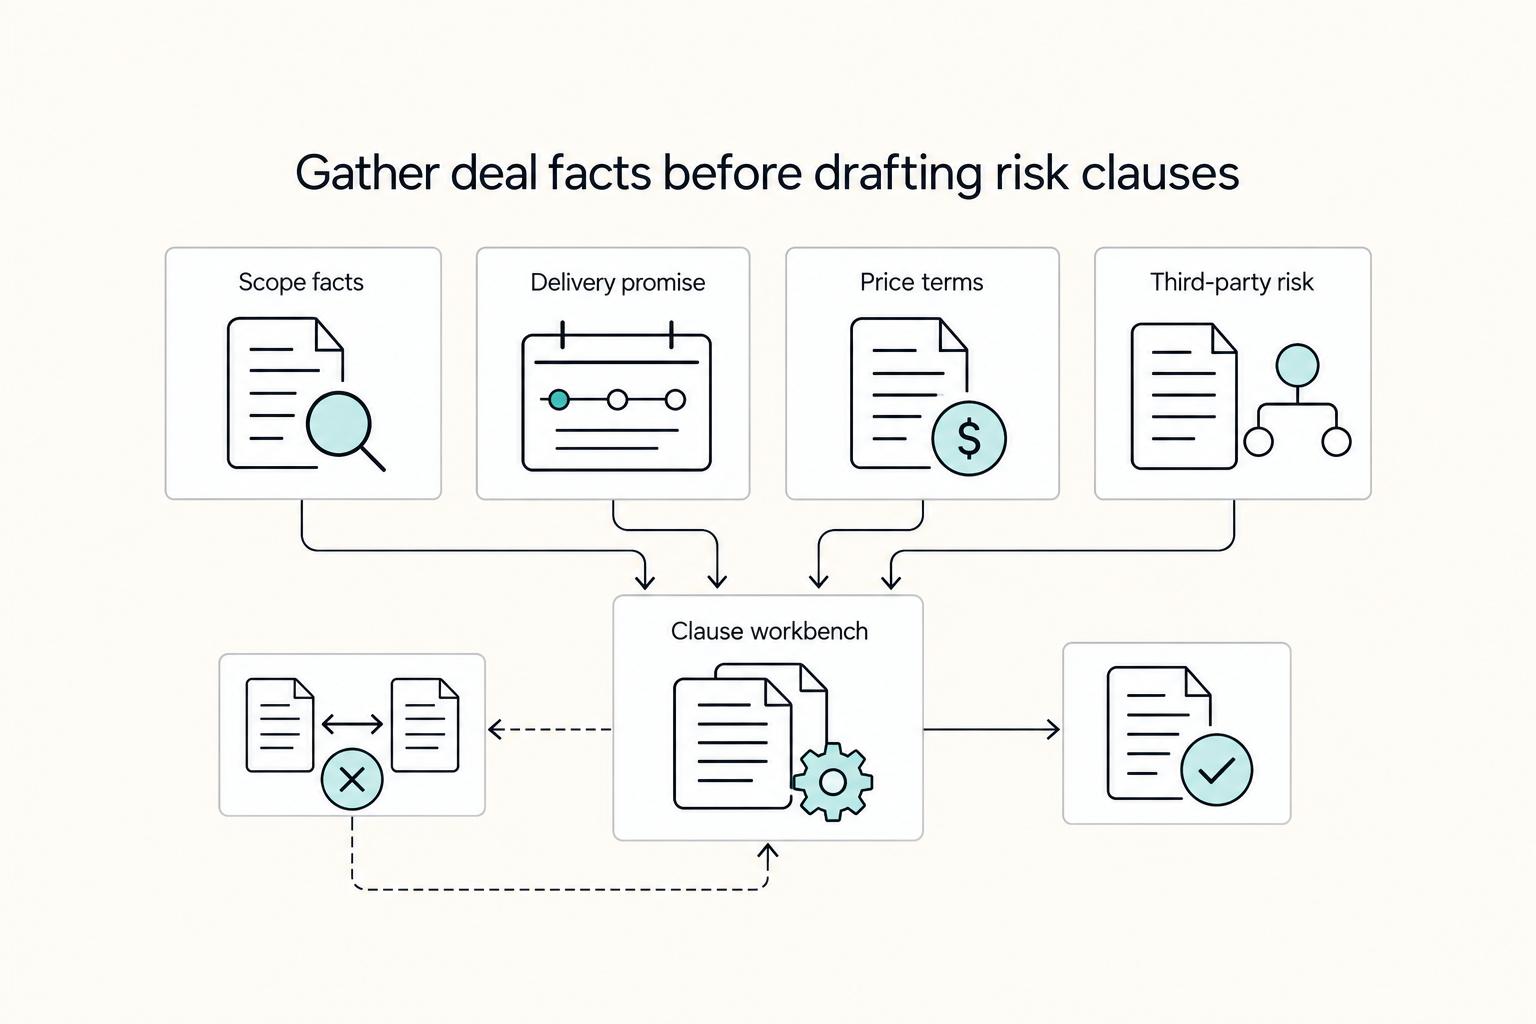
Assemble the deal facts first. Editing liability text without complete inputs is where avoidable mistakes begin, especially when pricing and delivery commitments were made in different channels.
| Input | What to collect | Detail |
|---|---|---|
| Deal record | Current draft, prior redlines, and all commercial promises from email or chat | Organize notes by scope, payment, additional fees, and change handling |
| Contracting parties | Legal entity names, signer names, and signature authority | Keep party details consistent across signature and invoice information |
| Discovery notes and scope | Goals, constraints, deliverables, and dependencies in plain language, then turn them into your SOW | Add a short risk list before legal edits, including scope creep, IP ownership questions, and payment timing risks |
| Commercial terms | Payment schedule, deposit terms, and written approval rules for changes | Clarify when additional fees apply so scope growth does not quietly become unpaid work |
| Unresolved items | Contract inputs that still need confirmation, especially IP ownership or assignment terms and change-control details | Use this page as your pre-sign check during every redline round |
When this prep is done well, later clause edits move faster because each edit can be tested against concrete deal inputs. For classification-specific language, use Independent Contractor Status: The Most Important Clause for Avoiding Misclassification.
Separate Limitation of Liability from Indemnification before negotiating#
A limitation of liability restricts the damages or categories of loss recoverable under the agreement. An indemnity allocates specified losses or claim-handling costs to one party. Many service indemnities concern third-party claims, but wording can also reach direct claims. Separating the clauses helps you inspect them; it does not make their interaction disappear.
For example, a client’s claim that your work was late is a direct contract claim. A photographer’s claim that an image in the deliverable infringes copyright is a third-party claim. Identify which clauses address each scenario and whether the same cap applies.
Mark phrases that can widen exposure. Check whether consequential or other listed damage categories are excluded, included, or unclear, and whether the limit applies to all causes of action in the aggregate.
Use one realistic project scenario to compare exposure with and without a clear cap. This keeps negotiation tied to commercial impact, not abstract drafting style.
Define the cap amount, measurement period and exceptions#
Choose an amount that reflects the engagement’s value and plausible downside. A fixed sum is easy to calculate; a fees-based limit needs a defined base. Fees paid can be much lower than fees payable early in a project. A rolling twelve-month base also changes over time. State whether the limit is aggregate across all claims or resets for each claim, and whether defense costs consume it.
Illustrative comparison: a $10,000 project is half paid when an alleged breach occurs. A cap based only on fees paid could be $5,000; one based on the total project fee could be $10,000. An aggregate $10,000 cap applies once across covered claims, whereas a $10,000 per-claim cap could allow two separate covered claims to reach $20,000. A carve-out or separate indemnity cap may change the result. These are drafting choices, not legal conclusions that either clause is enforceable.
Ask for the proposed amount, the fee base, the measurement date and the claims covered. Put those choices in the text rather than relying on the phrase reasonable cap.
A cap does not replace a clear scope. Specify outputs, client inputs, acceptance and included revisions, then decide which remaining losses you are willing to accept.
Check how liability, indemnity, warranty, confidentiality and remedies interact. Look for notwithstanding language, exclusive-remedy wording and exceptions that make one section override another.
Enforceability depends on the governing law and contract context. For example, section 2 of the UK Unfair Contract Terms Act 1977 prohibits excluding or restricting liability for death or personal injury resulting from negligence, and subjects restrictions on other negligence loss to reasonableness. Its application has statutory limits and exclusions; it is not a worldwide rule for every freelance contract.
Narrow the Indemnification Clause to real third-party risk#
For each indemnity, identify the triggering claim, whose conduct caused it, covered losses and claim procedure. A client may request protection for infringement in work you supply. You may request protection for claims arising from client-supplied materials. Allocation should follow the agreed responsibilities and exclusions, with the cap interaction stated expressly.
| Indemnity item | What to define | Detail |
|---|---|---|
| Trigger events you control | Specific triggers tied to your acts or deliverables | Allocate defined claims to the responsible conduct or materials, with express exclusions |
| Covered losses | State what is covered and make a clear call on damage categories | Specify damages, settlements and defense costs; state whether they consume the cap |
| One-way indemnity | Flag risk that both sides influence and propose narrower allocation tied to control | One-sided language can shift legal fees and damages in ways that do not match who controlled the risk |
| Claim-handling procedure | Define notice, defense control, cooperation duties, and settlement approval | The clause alone should show who notifies whom, who controls defense, and who approves settlement |
| Hold harmless wording | Check hold harmless language against indemnity scope and the cap text | A capped liability clause may offer limited protection if indemnity remains broad or uncapped |
An obligation to defend can create costs before a claim is decided. Agree how notice works, who selects counsel, who controls defense, what cooperation is required and whether a settlement needs approval. Do not assume legal fees are inside the general damages cap unless the text makes that clear.
Review every use of indemnify, defend and hold harmless. Ask what each promise requires under the chosen law, and remove duplication or conflicting procedures. A clause drafted for public procurement is not automatically suitable for a private freelance engagement.
Keep excluded causes explicit: for an IP indemnity, discuss client-provided assets, unauthorized modifications, combinations outside the agreed scope and use outside the licensed purpose. These are negotiation topics, not automatic exemptions.
Tie risk clauses to Scope of Work, Payment Terms, Change of Scope, and Termination#
Risk clauses work better when the operating clauses support them. If scope, billing, and exit terms are vague, even strong liability language can be hard to apply in real project conditions.
| Clause | What to align | Detail |
|---|---|---|
| Scope of Work Clause | What is included, what is excluded, and what client inputs are required | Clear acceptance language can help reduce unpaid rework risk |
| Payment Terms Clause | Agreed deposits, service periods, hours or deliverable milestones | State the due date and trigger for each payment; a booking deposit can precede delivery |
| Change of Scope Clause | Documented approval for added tasks, timeline shifts, and fee impact before execution | Quick verbal approvals may feel faster now but can create harder scope and payment disputes later |
| Termination | Wind-down duties, final invoice handling, return or destruction obligations, and survival terms | Abrupt stops without exit steps can become payment and ownership fights |
| Clause-mapping check | Link each risk clause to the relevant operating provisions in the same contract | Check cross-references and document precedence; one clause may interact with several others |
Tie invoices to agreed dates or milestones and define review and acceptance terms. A booking deposit may be due before delivery; do not make every payment depend on a completed output.
Map risk clauses to the relevant scope, payment, change and termination provisions. Check multiple cross-references and the order of precedence between the MSA and SOW.
Decide what your business structure and insurance can actually cover#
Entity structure, contractual limits and insurance perform different jobs. A U.S. LLC generally separates business obligations from an owner’s personal assets, subject to applicable exceptions; it does not cap the company’s contract liability or pay a claim. A liability cap restricts covered contractual exposure. Insurance may fund eligible losses within its policy terms.
Confirm the named insured and contracting entity, the services covered, exclusions, deductible, territorial scope, policy limit and any defense-cost treatment. Ask the insurer or broker specifically about contractual indemnities and defense obligations; a certificate alone does not show that every promise in the contract is insured.
Keep entity structure separate from worker classification. Using an LLC or an independent-contractor label does not itself decide employment status; review that issue separately if the working arrangement raises it.
Before accepting an insurance obligation, check that the actual policy can satisfy it and that any uninsured exposure is understood. Do not promise coverage simply because a certificate lists a large limit.
A short pause before you sign is usually easier than fixing a mismatch after obligations are already live. If insurance obligations are part of the draft, Do Freelancers Need Business Insurance? A Complete Guide is worth reviewing before you sign.
Lock Governing Law, Jurisdiction, and Dispute Resolution for cross-border work#
Lock these terms as one package before you sign. In cross-border deals, unclear governing-law language can trigger arguments about which law applies before the underlying dispute is even addressed, increasing time and legal cost.
Governing law identifies the legal system used to interpret the agreement; jurisdiction identifies the courts selected to hear disputes. An arbitration provision needs its own forum, rules and process. Review the package for consistency and enforceability rather than choosing a distant forum solely to appear neutral.
Define the escalation or mediation process, deadlines and what happens if it fails. If arbitration is chosen, identify the rules, seat and other required details with qualified drafting help. Do not let a discussion period obscure urgent remedies or limitation deadlines.
Redline the terms that quietly transfer all risk to you#
Use this pass to catch risk transfer before it gets normalized in later drafts. Broad language can make a deal look balanced while shifting most of the downside to you.
Flag all losses, arising in connection with, notwithstanding, defend on demand and unlimited. Each may broaden the obligation, but its effect depends on the full clause. Record the trigger, recipient, cost category and cap interaction before proposing a change.
A higher fee or narrower scope can be part of a counteroffer. If the remaining exposure is beyond your resources or coverage, propose a finite limit or decline that obligation instead of treating pricing as a cure.
| Client ask | Risk impact, counter language, commercial tradeoff |
|---|---|
| Broad damages wording | Record how exposure expands, propose narrower language, and note what you requested in return |
| Blanket indemnification text | Record overlap with other obligations, propose defined triggers, and note scope or fee movement |
| Broad defense obligations | Record potential cost shift, propose clearer limits, and note payment or acceptance protections |
Record the final result for each material issue: removed, narrowed, accepted with a defined limit or deliberately retained. Compare the execution copy with the agreed redline so an earlier exception does not return unnoticed.
If you want a cleaner starting point before redlining, draft a baseline services agreement with the Freelance Contract Generator.
Build a pre-sign evidence pack you can defend later#
Before you sign, build an evidence pack that ties scope, risk tradeoffs, and payment records to the final contract text. This record can help protect your position when memory and email threads diverge.
Recheck the risk package when scope, governing law, forum or contracting party changes. During delivery, retain approvals, acceptance records and change orders alongside the signed agreement; pre-sign notes alone cannot establish what happened later.
Check the final risk allocation before signing#
Use this short final check against the execution copy, then keep delivery records alongside it.
Confirm the cap amount, fee base, period, aggregate or per-claim treatment, loss categories and exceptions.
Confirm whether each indemnity and its defense costs fall under the general cap, a separate limit or an express exception.
Check triggers, exclusions, notice, defense control, cooperation and settlement approval.
Align scope, payment, change approval, document precedence and closeout with the negotiated risk terms.
Keep the signed execution copy, accepted schedules, redlines and approvals; add delivery, acceptance and payment records as work proceeds.
Frequently Asked Questions
What is a freelance liability clause, and where does it usually sit in a Freelance Contract?
A limitation-of-liability clause usually appears in the main services agreement or master services agreement and limits specified damages or losses. Check incorporated schedules, SOW precedence and indemnity exceptions too: another document can alter its reach.
Is Indemnification the same thing as a Limitation of Liability Clause?
No. A liability limit restricts covered exposure; an indemnity allocates specified losses or claim costs. An indemnity may sit inside the general cap, use a separate cap or be uncapped. The agreement must say which treatment applies.
Do I need both a Limited Liability Company (LLC) and a Liability Cap?
They address different risks. An LLC can separate business and personal obligations under applicable law, while a cap limits covered contract claims against the contracting party. Insurance may cover eligible losses. None automatically substitutes for the other; confirm the correct entity signs and evaluate personal guarantees or other exceptions separately.
What should be excluded from my Liability Cap, and when?
Separate legally required exceptions from negotiated carve-outs. Governing law may forbid limiting particular liabilities; fraud, confidentiality, IP and payment obligations are also frequent negotiation topics, but no universal list makes them all uncapped. For each exception, ask whether a separate limit is possible, what costs it covers and whether insurance supports it.
Who should indemnify whom in a service agreement with a Third-Party Claim risk?
Allocate the defined claim to the party responsible for the relevant conduct or materials, with exclusions for causes outside that responsibility. For example, freelancer-created infringing assets and client-supplied infringing assets may call for different allocations. State defense procedure and cap treatment rather than relying only on a reciprocal label.
How should I choose Governing Law, Jurisdiction, and Dispute Resolution in cross-border contracts?
Choose governing law and a workable court or arbitration forum as a coordinated package. Consider the parties’ locations, dispute value, language, costs and enforcement needs. Specify any escalation process and review local enforceability before signing.
Try a related tool
Researched and edited by the Gruv editorial team. Gruv builds cross-border billing, payouts, and finance-operations software for global businesses.
Sources
Educational content only. Not legal, tax, or financial advice.
Related Posts

International Freelance Contract Clauses for Payment and Dispute Control
Send a written contract before any work starts. In cross-border freelance work, this is one of the simplest ways to reduce misunderstandings and protect the terms that matter most.
Do Freelancers Need Business Insurance Before Client Onboarding?
Make one decision first: buy coverage that matches your real exposure and the proof your contracts require, not the cheapest result on a quote page. The goal is practical and immediate: decide what to bind now, what can wait, and what documentation must be ready before kickoff.

Independent Contractor Status for Cross-Border Freelancer Contracts
An independent-contractor clause describes the intended arrangement; it does not decide legal status. Control over working methods matters, but the applicable test can also consider financial independence, permanence, the business relationship and the work’s place in the client’s business. Identify the worker’s location and the relevant tax and labor laws before drafting.