

Quick Answer
State the intended relationship, working independence, authority limits and commercial responsibilities, subject to mandatory law. Check the contract against the SOW and actual practice. Control over methods matters but is not a complete classification test; local rules may require additional facts. Confirm payee forms and payer reporting/withholding duties, then review operational changes promptly.
Independent contractor status is a system, not a sentence#
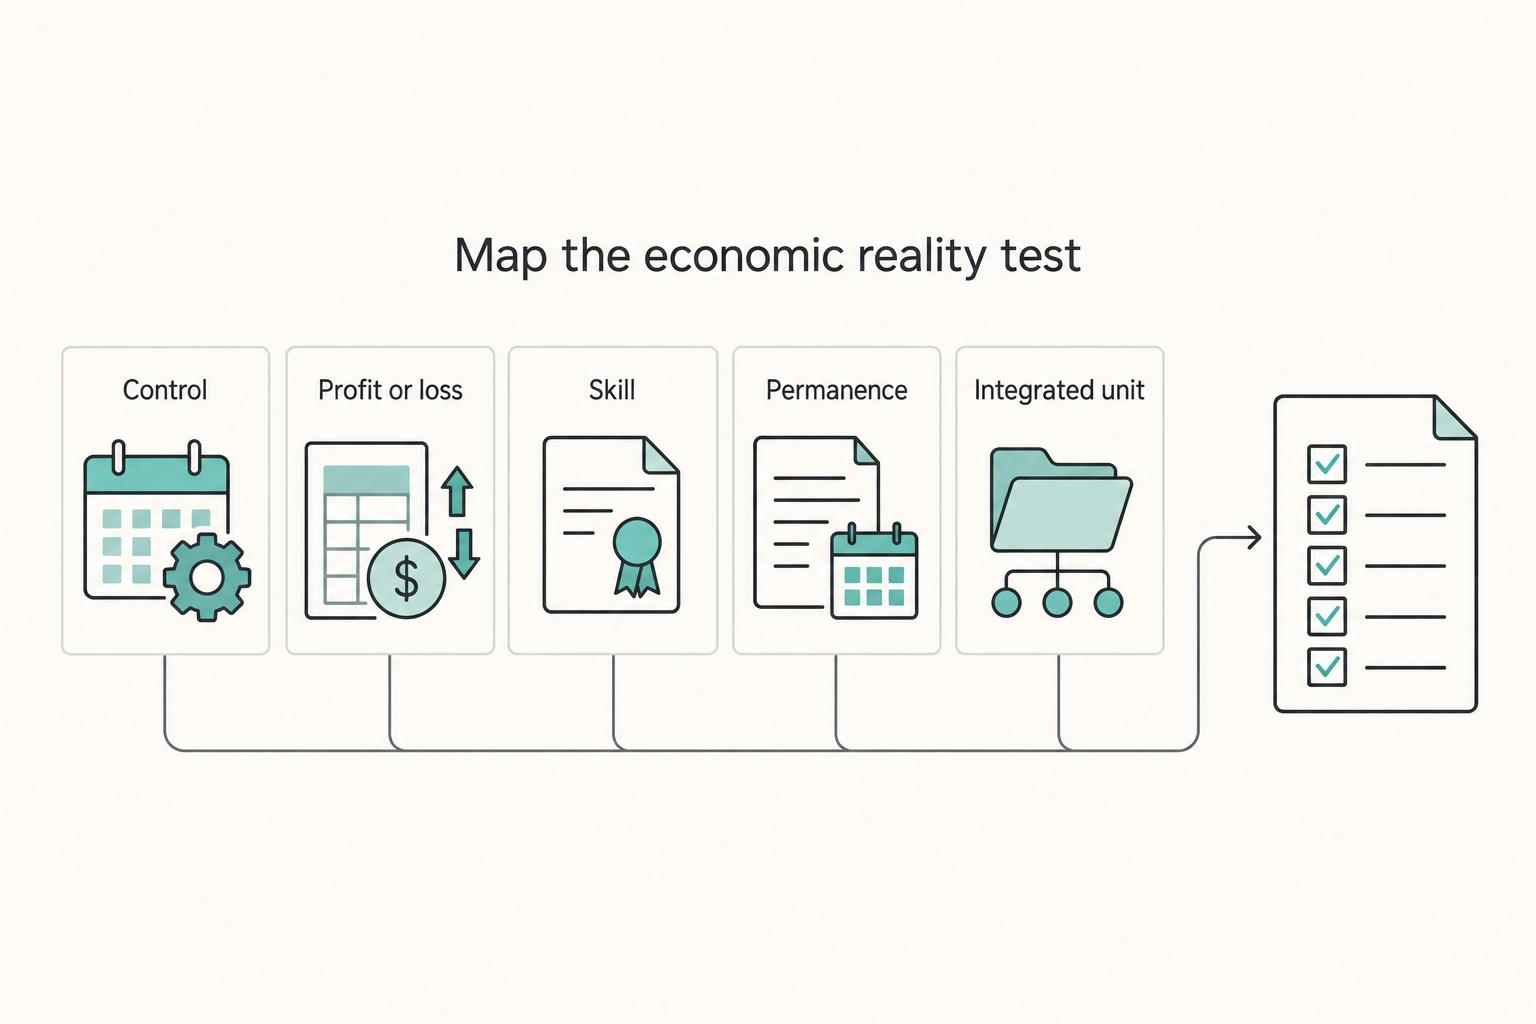
An independent-contractor clause describes the intended arrangement; it does not decide legal status. Control over working methods matters, but the applicable test can also consider financial independence, permanence, the business relationship and the work’s place in the client’s business. Identify the worker’s location and the relevant tax and labor laws before drafting.
A well-labeled agreement can still fail if onboarding, reporting, or approval mechanics pull the work back under employee-style control. That gap between paper and practice is where status problems get expensive.
Use this guide to prepare the clause and its supporting records for local review. U.S. federal tax, FLSA labor and state tests differ. As checked October 5, 2026, DOL materials identify a February 2026 proposed replacement rule and the May 2025 enforcement policy; the proposal is not itself a final rule. Distinguish the operative regulation, agency enforcement approach and relevant court/state law before applying a current test.
Start with the operating boundary, because every later redline should support it. Before the first redline, run this baseline checklist:
- Define the relationship in plain terms: the contractor controls method and execution, while the client approves deliverables, deadlines, and any clearly stated acceptance criteria.
- Draw the control boundary: list security or compliance constraints, then confirm that execution choices stay with the contractor.
- Flag employee-like control early: fixed office hours, manager-style supervision, and broad internal policy control are common red flags.
- Align all documents: the agreement, SOW, onboarding forms, and manager instructions should tell the same story.
- Save evidence of practice: keep the signed contract, SOW, invoices, and communication records that show outcome-based management.
This is not about winning an argument over labels. It is about making sure the contract, the work instructions, and the payment setup all describe the same arrangement.
Compare the status language with the SOW and actual onboarding. If the arrangement becomes employee-like, reassess classification and any payroll or statutory obligations. Editing the label alone cannot cure past or ongoing misclassification.
Keep negotiation concrete. If procurement asks for daily attendance, offer milestone reporting, response-time commitments, and prebooked collaboration windows. If a reviewer wants broad approval rights, narrow them to acceptance criteria and compliance exceptions. That keeps accountability intact without giving up control over how the work gets done.
State the boundary early and keep testing edits against it: the client controls outcomes, the contractor controls execution. When comments arrive from multiple reviewers, group them into control, authority, benefits, taxes, and operations, then clear the highest-risk cluster first so late edits do not quietly reintroduce employee-like terms.
With that baseline in place, draft the relationship clause around operating facts, not labels alone.
For a clause-by-clause walkthrough, read The Ironclad International Freelance Contract: 10 Clauses You Cannot Ignore. If you want to draft the SOW next, try the SOW generator.
Build the relationship clause around the intended working arrangement#
Describe the relationship, authority limits, intended benefits/tax handling and operational independence. These are useful contract terms, not a universal legal minimum or a substitute for classification. The contract cannot remove obligations that the applicable law imposes on either party.
The order matters. If you start with performance or security language before you define the relationship, later reviewers often draft from a control mindset, and the status clause ends up sounding decorative.
Build it in this order so the language stays clear and internally consistent:
- Independent Contractor Relationship: state this explicitly, then disclaim an Employment Relationship, Partnership, Joint Venture, and Agency Relationship.
- Authority to Bind: state that the contractor cannot make representations, commitments, or contracts on the client's behalf without prior written authorization.
- Benefits and taxes: state the intended commercial treatment, subject to mandatory law. The contractor handles their applicable filings; the client remains responsible for any reporting, withholding, employment or other duties the law assigns to it. A no-benefits sentence cannot waive statutory employee rights if the worker is legally an employee.
- Operational independence: state that the contractor controls method, schedule, and delivery approach, except for clearly listed security or compliance constraints.
Once those four points are set, you can test the rest of the agreement against them.
It helps to keep benefits and taxes in the same block. In practice, those points often get reviewed by different people, and separating them makes it easier for a stray employee-style reference to survive redlines. Treat the operational independence sentence the same way: carve out genuine security or compliance needs, but do not let those exceptions expand into ongoing direction about how the work must be done.
Use fixed hours, detailed supervision and broad policy control as review signals, not a complete test. The IRS weighs behavioral, financial and relationship facts. Where California’s ABC test applies, the hiring entity must also show work outside its usual business and an independently established business. Exemptions can change the applicable test, but a qualifying business-to-business exception does not automatically establish contractor status.
Finish with a consistency check across the agreement, SOW, and onboarding instructions so practice does not drift away from the clause. Once this section reads cleanly, make sure nothing else in the paper stack quietly reverses it.
For the U.S. federal labor context, read the independent-contractor rule guide alongside current DOL materials. Do not treat a proposed rule or an enforcement bulletin as interchangeable with the regulation.
Run a contradiction audit before you sign#
Most status problems are not obvious in the opening paragraph. They show up when the relationship section says one thing, the SOW says another, and the onboarding packet tells managers to treat the contractor like staff. That is why this audit should be a signing gate, not a cleanup task after approval.
| Check | Watch for | Rewrite toward |
|---|---|---|
| Control | Fixed hours; manager-style supervision; broad internal policy control | Deliverables, deadlines, and defined compliance limits |
| Reporting | Reporting that reads like ongoing oversight | Milestone or outcome accountability |
| Tool and access | Required tools or working methods that imply control over how the work is done | Coordination or security, not method control |
| Benefits | References to employee-style benefits | Clarify intended benefits subject to mandatory rights; do not erase statutory entitlements |
| Authority | Language implying authority to bind the company | Written-authorization language |
Run the review on the latest versions only, and put the agreement, SOW, onboarding guide, and any manager instructions side by side. The audit works best when one person owns the status issue and marks every conflicting phrase in one pass.
Review the agreement, SOW, onboarding materials, and operating instructions together, then check for the contradictions that matter most:
- Control check: if you see fixed hours, manager-style supervision, or broad internal policy control, rewrite the language to focus on deliverables, deadlines, and defined compliance limits.
- Reporting check: if reporting reads like ongoing oversight, rewrite it to milestone or outcome accountability.
- Tool and access check: if required tools or working methods imply control over how the work is done, clarify that they are for coordination or security, not method control.
- Benefits check: clarify intentional commercial benefits and mandatory rights. Removing a benefit reference does not establish independent status or lawfully waive an employee’s entitlement.
- Authority check: tighten written-authorization language anywhere the draft could imply authority to bind the company.
The point is not to sanitize language. It is to remove clauses that change the practical allocation of control.
Use a simple decision rule: if fixed hours, supervision, and policy control appear together, pause signature and renegotiate before final legal approval. One stray phrase can sometimes be fixed with a narrow edit. A cluster of them usually means the actual working arrangement has drifted past what the status language can honestly support.
Capture each issue in a status-consistency sheet: document section, risky text, factual conflict, proposed change and owner. Follow the agreement’s amendment process and required formalities. A signed amendment records a change; it does not override mandatory classification law or erase the earlier working relationship.
Once the documents stop contradicting each other, lock the tax and payment side to the same treatment before the first invoice goes out.
Document tax and compliance responsibilities with an evidence pack#
Do not leave tax treatment and payment setup to side emails. A one-page evidence pack before the first invoice keeps the administrative record aligned with the agreement, and it gives both sides a short list of things they can actually verify.
It also gives finance, AP, and the contractor the same reference point when setup questions come in. Without that, even a clean agreement can produce inconsistent forms, mismatched payee records, or delayed first payments.
This is not extra paperwork for its own sake. It makes sure tax handling, recordkeeping, and contractor responsibilities are explicit before money starts moving. Keep the pack focused on items you can confirm from the signed agreement and onboarding records:
- Payer reporting and forms: identify payee tax status and payment type. U.S. nonemployee service compensation generally uses Form 1099-NEC where required, not a blanket 1099-MISC instruction. Apply current thresholds, exceptions and payment-channel rules.
- Contractor tax line: identify the contractor’s own applicable tax/social-insurance responsibilities. Schedule SE is relevant to U.S. self-employed individuals under its rules, not every foreign contractor or entity.
- Private foreign-asset review: where relevant to the contractor’s U.S. tax status, have their adviser assess Form 8938 and FBAR separately. Form 8938 accompanies the applicable return; FBAR is a separate FinCEN filing. A cross-border contract alone triggers neither.
- Withholding line: distinguish employee payroll from backup withholding and any foreign-payee/source-income withholding. Determine the applicable form and exemptions before configuring AP.
- Records line: retain signed terms, invoices, tax documentation and payment records with access appropriate to the information.
- Open-question log: name the missing tax/status fact, reviewer, next action and due date; keep sensitive personal account material out of the shared client pack.
If a tax question is unresolved, mark it pending with the fact needed, owner and decision date. Do not omit an applicable legal duty simply because the contract or onboarding file fails to mention it. Keep personal foreign-account reviews with the contractor’s adviser rather than sharing account details in the client’s general onboarding folder.
| Line item | What to confirm | Owner | Proof kept |
|---|---|---|---|
| Payee/forms | Legal identity, tax status, payment type and applicable reporting form | Client finance | Validated tax documentation and classification note |
| Contractor taxes | Own income/social-insurance obligations under applicable law | Contractor/adviser | Private tax review; relevant acknowledgment |
| Foreign-asset review | 8938/FBAR applicability if relevant to U.S. status, independently of the contract | Contractor/adviser | Private dated review; no general client account-data dump |
| Withholding | Payroll, backup withholding and foreign-payee rules distinguished | Client finance/adviser | Applicable documentation and payment configuration |
| Retention | Custodian, permitted access and retention rules identified | Both sides | Records policy and folder permissions |
Keep the pack in the same folder as the signed agreement and payment setup so it can be checked quickly if questions come up.
Before payment setup, verify the contracting/payee identity, applicable tax documentation and authorized payment route. Resolve critical mismatches with a named owner; do not delay an already-due lawful payment merely because an unrelated internal checklist entry is incomplete.
With the administrative file in order, move to the forum terms that decide where and how a dispute gets handled.
Set Governing Law, Jurisdiction, and Dispute Resolution without guesswork#
These terms look like boilerplate until a dispute arrives. At that point, a mismatch between governing law, venue, and process can eat time before anyone even reaches the substance of the claim. Treat Governing Law, Jurisdiction, and Dispute Resolution as one decision set, not three disconnected inserts.
The chosen law and forum can be in different countries. The practical questions are whether the forum can apply the selected law, enforce the agreement and handle the expected claim at a proportionate cost. Matching country names is not a universal requirement.
Start with a clear choice-of-law clause, then align jurisdiction and dispute resolution so the contract is usable in practice for both sides. Old forms and inattentive drafting still create this mismatch. For cross-border work, that gap increases legal and financial risk when the terms are not appropriate for the jurisdictions involved.
Use this pre-sign sequence:
- Choose Governing Law.
- Choose Jurisdiction that can realistically apply that law.
- Choose a dispute resolution path based on claim size, cost tolerance, and speed needs.
- If venue is impractical for either side, negotiate a neutral forum or remote-first procedure before signing.
- Require any forum change to be made in a signed written amendment.
That written-amendment rule matters because venue changes often get floated informally once a disagreement starts.
Quick negotiation check:
| Question | If yes | If no |
|---|---|---|
| Can both sides realistically use the proposed venue? | Keep it and document why | Move to a neutral forum or remote-first path |
| Can the forum apply the chosen law, and are mandatory rules addressed? | Confirm enforceability and costs | Revise the choices with local review |
| Is the dispute path fit for your likely claim profile? | Keep current process | Rework the process choice before execution |
If either side would avoid bringing a real claim because the forum is too costly or too remote, the clause set needs work.
The practical checkpoint is simple: the selected law should be one the chosen forum can realistically use, and the dispute path should fit the kind of claim you are most likely to have. Once that is settled, turn to the clauses that decide what each side owes if the project changes or a claim appears.
Add risk-allocation clauses that support status protection#
Risk-allocation clauses should clarify exposure, not create open-ended obligations or vague control. Draft them so they support the same independent working relationship described elsewhere in the agreement.
These are the terms that usually decide whether an unpleasant exit stays manageable or turns into a payment fight.
- Termination Clause: set written notice and confirm payment of amounts due through termination, including approved pre-incurred non-cancellable expenses.
- Limitation of Liability: keep risk allocation tied to the services and the overall deal risk, rather than leaving exposure open-ended by default.
- Indemnification: state when indemnity applies and where it does not, and avoid one-way drafting that shifts all third-party risk to the contractor.
- Reimbursement Clause: keep reimbursement scoped with pre-approval expectations and documentation requirements so expense handling stays clear.
Do not draft them in isolation.
Check these clauses against your SOW and payment terms so they reflect the same working model as the status language. If a draft combines broad termination discretion, uncapped exposure, one-way indemnity, and loosely scoped expenses, escalate it for revision before anyone treats the paper as finished.
As a final test, run one likely dispute scenario. If termination happens mid-scope, both sides should be able to tell from the clause text what is owed and what happens next. If they cannot, the clause set is still too loose. Use an actual project fact pattern from the SOW when you do this. Drafting problems show up faster when you test a realistic stop point, invoice status, and expense record.
If the draft still drags at this point, use targeted negotiation language instead of reopening the whole deal.
Use negotiation scripts that keep deals moving#
Do not trade compliance with applicable classification law for a higher fee. Negotiate scope, timing and delivery accountability on their own merits; if the client needs an employment arrangement, assess that arrangement rather than preserving a contractor label at all costs.
Once status gets traded against rate or scope, it is hard to get it back without reopening the entire deal.
These scripts work because they are short, specific, and tied to a drafting fix:
- Authority to Bind: "I can't accept language implying agency; please use written-authorization-only wording."
- Benefits wording: "Please distinguish the commercial benefit arrangement from any rights mandatory law requires."
- Control overreach: "I can commit to deliverables and milestones, but not employee-style supervision."
- Performance enforcement: "If work misses Statement of Work requirements, let's define cure steps and termination rights in writing."
- Status anchor: "Please align control and approval terms with the Independent Contractor Relationship clause."
They also give procurement or legal a sentence they can accept or reject directly, instead of forcing a broad debate over classification theory.
For rigid enterprise templates, fix agency language, control language, and status conflicts first. For flexible startup paper, bundle more edits in one pass. The priorities are the same, but the pace is different. That is often the difference between a fast fix and a circular email chain.
If there is pushback, offer fallback language that preserves accountability without shifting status: milestone check-ins instead of daily supervision, objective acceptance criteria instead of broad approval rights, and written authorization for specific acts instead of standing authority. Before signature, confirm the draft still states independent-contractor status and that any monitoring rights are tied to Statement of Work performance, not day-to-day direction.
Once the wording is settled, do one last paper check before anyone signs, then test the same points again after work begins.
Sanity checks before signature and in the first 90 days#
Signature is not the finish line. The first 90 days are where clean drafting either holds up or gets quietly undermined by onboarding habits, manager requests, or payment setup drift.
This is where a good clause can get undercut by small habits, like treating milestone updates as manager approvals or asking for daily attendance after the SOW was written around deliverables.
Do one final pre-sign consistency review, document the result, and then confirm during the first 90 days that day-to-day execution still matches the signed terms. Before signature, complete this checklist and save a signed classification-consistency memo:
- Gather the final contract draft, SOW, payment/tax setup, and onboarding requirements.
- Confirm status language is consistent across the package, including the relationship clause.
- Review Termination, Limitation of Liability, Indemnification, Governing Law, Jurisdiction, and Dispute Resolution together so they do not conflict.
- Apply the contract's document hierarchy if any terms conflict.
- Confirm the Effective Date, term, and any renewal language are clear.
- Record who reviewed, what conflicts were found, and what edits were accepted.
If the contract has a document hierarchy, use it, but do not rely on hierarchy alone to excuse contradictions you already know about.
Use periodic checks in the first 90 days as an internal practice, not a statutory safe harbor. Reassess sooner if control, exclusivity, business activity or the worker’s location changes. Where the facts support employment, address the classification and resulting obligations; a cosmetic contract amendment is insufficient.
Use the same three questions at each check:
- Who controls day-to-day execution in practice?
- What approvals are required in practice?
- Do those approvals match the signed SOW and status clause?
Record changed facts, identify the applicable test and decide what operating changes, classification or payroll correction are required. The paper should reflect the actual arrangement rather than conceal it.
Store the memo, amendment trail, and acceptance emails together with clear version names and dates. That simple record set is usually enough to spot drift early instead of reconstructing it months later.
Those checks answer most operational questions, but a few issues come up often enough to address directly.
Put your clause system into practice on your next contract#
Keep the clause, SOW, payment setup and actual work consistent with the intended arrangement, then test that arrangement under the applicable law. Consistency improves the evidence file but does not by itself prove independent status.
If you only remember one point, remember the comparison test: does the contract describe the same working relationship your client will actually run?
- Document the intended relationship, authority, operations and tax responsibilities subject to mandatory law; test the facts under the applicable classification rules.
- Keep one final working file set, including the agreement, SOW, redlines, and accepted edits, so contradictions are easy to spot later.
- Resolve conflicts on control, authority, termination, and payment before minor commercial edits.
- Check current primary law and agency materials; distinguish final rules, proposals, enforcement policy and local tests.
- Set a post-sign review checkpoint so actual practice does not drift from the signed terms.
If day-to-day control starts to tighten, renegotiate before kickoff or amend the operating approach quickly once work begins. Early-termination disputes show how fast payment expectations can become contested, so write termination consequences clearly and review them with local counsel before relying on assumptions.
For the business-structure side of the decision, review Sole Proprietorship vs. LLC: The Definitive Guide for Global Freelancers.
Frequently Asked Questions
What is an independent contractor clause, and what must it include?
It records the intended non-employment relationship, operational independence, authority limits and agreed commercial responsibilities. Include terms suited to the actual engagement and applicable law; there is no single clause checklist that guarantees contractor status everywhere. Benefits and tax wording cannot waive mandatory rights or shift a payer’s statutory duties.
Does an independent contractor clause by itself prevent worker misclassification?
No. Classification follows the applicable legal test and actual facts, including any relevant right to control. Working-method independence can help but does not satisfy every test by itself. A contract, 1099 or company registration does not automatically establish independent status.
Can a contractor ever represent or bind the company?
Sometimes, but it should be narrow, written, and jurisdiction-specific. The default position should be no authority to bind unless there is prior written authorization for a defined act. Standing authority language is where trouble starts. Even when authority is granted, the language should be reviewed locally.
Who handles taxes under an independent contractor relationship?
A correctly classified U.S. self-employed individual generally handles their own income and self-employment tax. The payer retains applicable reporting and withholding duties: independent status does not exclude backup withholding or withholding on certain U.S.-source payments to foreign persons. Determine payee status, work location, source and documentation rather than using a universal “no withholding” instruction.
What wording most often conflicts with independent status?
Fixed hours, detailed supervision and broad approval over methods are review signals. Also test financial and relationship facts and any additional local criteria; under an applicable ABC test, freedom from control alone is insufficient. Genuine outcome acceptance or security requirements must be assessed in context.
How do Termination, Indemnification, and Limitation of Liability affect classification risk?
They do not determine status by themselves. They matter because they should fit the same working relationship as the rest of the agreement, and because lopsided combinations can create avoidable risk. They can also obscure what is owed when a project stops. Review them under the law that governs the deal, especially if the draft combines broad termination discretion, uncapped exposure, one-way indemnity, and loose expense language.
How should freelancers choose Governing Law, Jurisdiction, and Dispute Resolution in cross-border contracts?
Choose a forum and process both parties can realistically use, considering claim size, cost and enforcement. Governing law and venue need not be in the same country. A choice-of-law clause does not guarantee that mandatory worker protections or public-law tax obligations are displaced. Review cross-border enforcement locally.
Watch
Independent Contractor Clause: Avoid Misclassification
Try a related tool
Researched and edited by the Gruv editorial team. Gruv builds cross-border billing, payouts, and finance-operations software for global businesses.
Sources
Educational content only. Not legal, tax, or financial advice.
Related Posts

International Freelance Contract Clauses for Payment and Dispute Control
Send a written contract before any work starts. In cross-border freelance work, this is one of the simplest ways to reduce misunderstandings and protect the terms that matter most.

Sole Proprietorship vs LLC for Global Freelancers in 2026
For most freelancers in 2026, the practical default is still simple: use the simplest structure you can run cleanly, then formalize when risk actually rises. If your work is still in validation mode and the downside is contained, a sole proprietorship is often the practical starting point. When contract exposure, delivery stakes, or dispute risk starts climbing, forming an LLC deserves earlier attention.
DOL Independent Contractor Rule in 2026: Proposal and Current Standards
**Status checked 5 October 2026:** DOL’s official page still identifies the February 2026 action as a proposal, and says its comment period **closed on 28 April 2026**. The NPRM, published 27 February under RIN 1235-AA46, proposes replacing the 2024 FLSA interpretation with a modified 2021-style analysis and using the analysis for FMLA and MSPA. A proposal is not a final rule with an effective date.