
Quick Answer
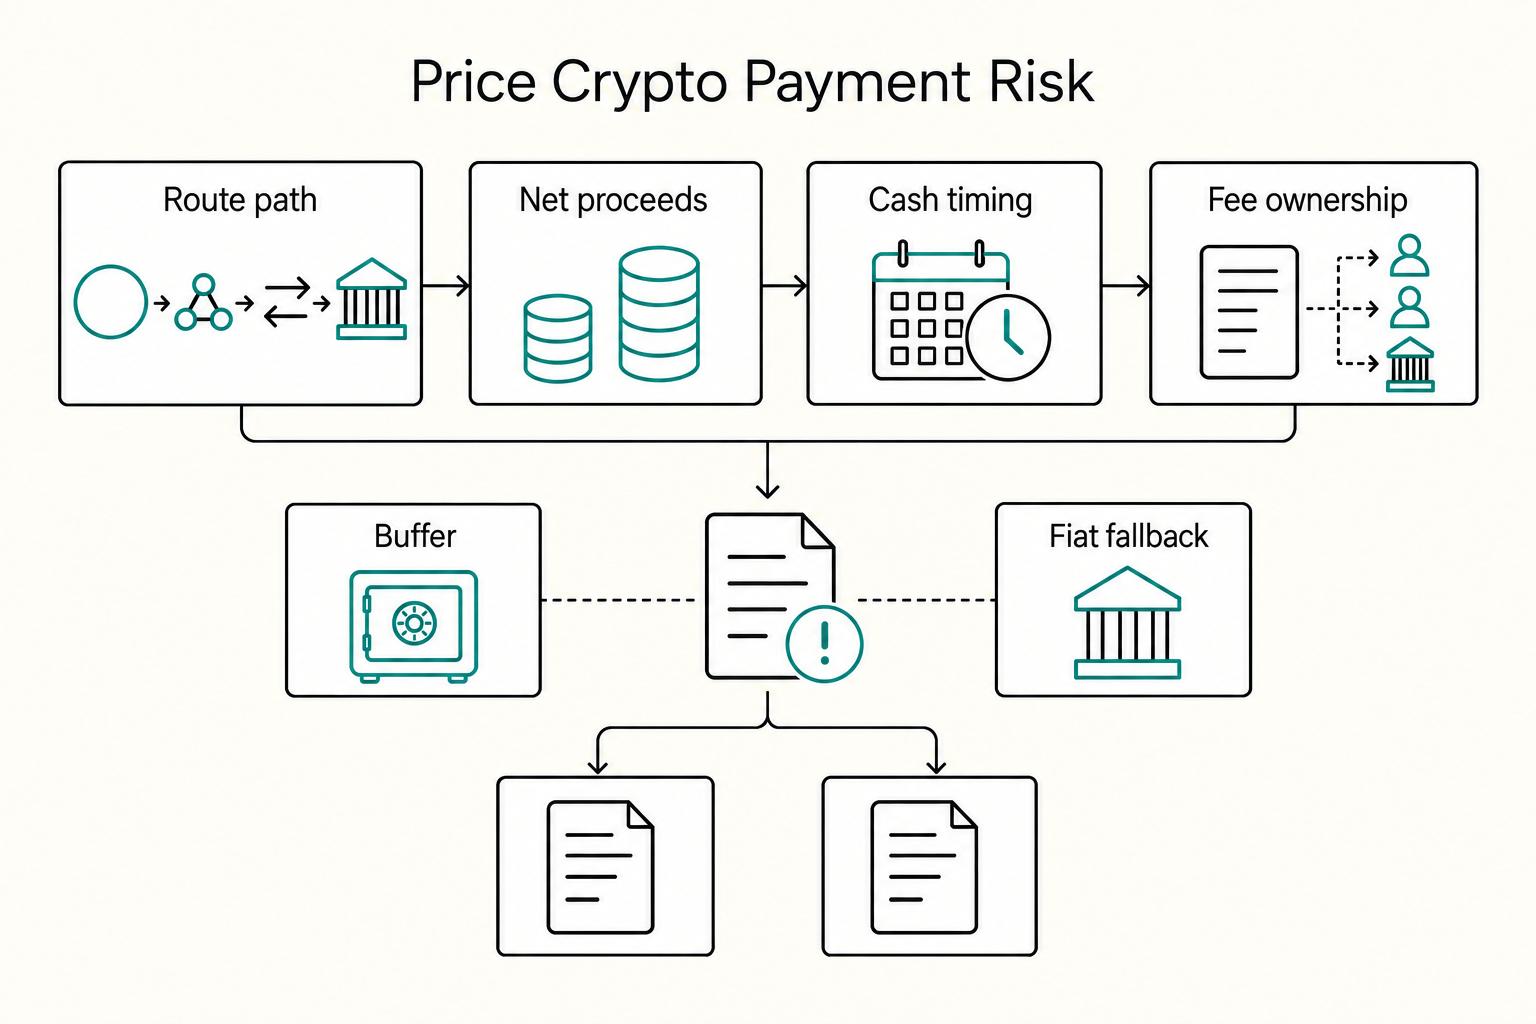
Decide whether a crypto route fits the invoice before work starts. Specify the exact asset and network, verify successful receipt, separate conversion from bank availability, account for stablecoin and custody risks, and resolve an unknown first transfer before switching to a fallback rail.
When crypto payments actually work for freelancers#
Crypto payments make sense only when they improve how reliably you get paid after you plan conversion, compliance, and recordkeeping up front. They can reduce friction in some international setups where traditional platforms add fees, restrictions, or extra steps. They also move risk onto conversion timing, exchange-fee exposure, and documentation quality, so use a simple acceptance test before you agree:
- Can you confirm receipt and convert to usable funds on terms you understand?
- Do you already know how you will manage conversion timing and exchange costs?
- Can you keep records that support legal and tax compliance and any later payment dispute?
That is the core tradeoff: crypto can remove one bottleneck while creating another. A payment can arrive successfully and still leave you with less cash than expected if conversion is handled poorly. If you do not actively manage when and how you convert, you can lose value.
Treat crypto as a payment rail with operating controls, not a shortcut. Plan conversion and compliance before the first transfer, then set up the tools you need to run cleanly, usually a wallet plus invoicing and tax apps.
That is the lens for the rest of this article: when crypto is practical, when another rail is a better fit, and which controls protect your cashflow. For a step-by-step walkthrough, see How to Get Paid in Crypto as a Freelancer (and Manage the Risks).
What freelance crypto payments actually include#
Crypto payments are client-to-freelancer transfers on blockchain rails, and in practice they are often made in stablecoins such as USD₮ or USDC. Judge them by execution, not headlines: can you confirm receipt, convert if needed, and move funds reliably?
Three layers to separate#
Treat the flow as three separate jobs:
| Layer | Role |
|---|---|
| Client platform | where the client relationship is managed |
| Payout provider | a service that may help invoice, collect, route, or settle funds |
| Your receiving side | your wallet, plus your invoicing and tax apps for records |
If one layer works and another fails, "payment sent" still does not mean "money usable."
What to verify before the first transfer#
Confirm the exact asset, blockchain network, token contract where applicable, destination address, and any required memo or tag against the receiving wallet or provider’s current deposit instructions. A token standard is not a network name. Check that the receiving service supports that precise asset/network combination and any native or bridged version; an address that looks compatible is not sufficient.
Translate marketing claims like "near-instant" or "lower cost" into outcomes you can verify:
- confirmed receipt in your wallet or provider account
- successful conversion if you do not want price exposure
- successful withdrawal from your payment workflow to your preferred account
Even with smart-contract escrow, do not assume guaranteed recovery, refunds, or support quality. For related wallet context, see The Best Crypto Wallets for Freelancers.
Decide accept with conditions or decline before you start work#
Make the go-or-no-go decision before any billable work. Accept crypto only when the terms protect your cashflow, and decline when price or settlement-timing risk lands on you.
For fixed-fee projects, payment value needs to stay predictable. If the terms leave you exposed to volatility or unclear settlement timing, you are taking on financing risk, not just delivery risk.
A practical decision table#
Use this as a control checklist, not a fixed rule.
| Outcome | When it fits | Why | Required terms |
|---|---|---|---|
| Accept | Terms are clear before work starts and value protection is practical | Operational and value risk are more contained | Written terms, confirmed wallet destination, conversion plan if needed |
| Accept with conditions | The client can pay in a dollar-linked stablecoin, but tighter controls are still needed | A stablecoin targets a reference price but retains depeg, freeze, issuer and off-ramp risks | Stablecoin preference, written payment terms, wallet-address confirmation before transfer |
| Decline | Terms stay unclear or value certainty is not protected | Downside risk is too high for a fixed-fee invoice | Use cash, bank transfer, or another rail |
Crypto can look faster, and stablecoins are often described as moving around the clock and settling quickly, while banks may process in daily batches. But faster possible settlement is not the same as dependable usable cash.
Treat Bitcoin and Ethereum as price-risk terms#
If a client wants to pay a fixed-fee invoice in Bitcoin or Ethereum, treat that as a volatility term, not as neutral payment language. Broader crypto markets can swing materially. That can break value certainty between invoicing and usable funds.
You can still accept in limited cases, but require conversion terms you can execute on receipt. Crypto processors that offer invoicing and instant fiat conversion can reduce operational friction.
Stablecoins can be workable, but only with explicit controls#
A dollar-linked stablecoin targets a reference value, but that does not guarantee its market price, your redemption eligibility, or a successful cash-out. Check issuer, depeg, freeze, custody, and off-ramp risks alongside transfer details. For example, Circle’s USDC terms outside the EEA restrict direct redemption to eligible registered Circle Mint users; terms differ by jurisdiction.
- whether payment will be in a dollar-linked stablecoin
- a conversion plan if you need fiat-value certainty at receipt
- written payment terms before transfer
Put one verification checkpoint before first transfer#
Verify destination details through a trusted channel before the first transfer and whenever instructions change. Compare the full address and required memo or tag with the receiving service’s instructions; do not rely on a copied address from recent transaction history. Test a small amount on the exact supported route and confirm credit before sending the balance.
Keep a retrievable record: invoice terms, written confirmation, wallet address used, and asset/conversion notes. If the client resists basic written confirmation, treat that as a warning sign. For many freelancers, cash remains the safest and simplest baseline.
Calculate the real cost to receive not just the headline fee#
Calculate from invoice total to spendable cash before you quote. If you cannot estimate both net proceeds and delay range with reasonable confidence, add a risk buffer or use non-crypto terms.
A single visible fee is not your real cost. What matters is the amount you can actually use after stacked deductions and timing risk. Depending on the route, costs can include card percentage fees, fixed fees, cross-border surcharges, FX surcharges, chargeback-related drag, and exchange transaction fees when crypto is bought, sold, or traded.
Compare every path from gross invoice to usable cash#
Use the same starting invoice amount for every rail, then subtract each cost layer in order.
| Path | From invoice total to final spendable amount | Main uncertainty to score |
|---|---|---|
| CoinGate | Invoice total minus all route-specific fees and conversion costs you can verify in writing | End-to-end route clarity and recovery process if payout or withdrawal stalls |
| Ruul | Invoice total minus all route-specific fees and conversion costs you can verify in writing | Payout timing, conversion terms, and support time if funds do not arrive as expected |
| Nebeus | Invoice total minus all route-specific fees and conversion costs you can verify in writing | Off-ramp completion, bank-out completion, and intervention time if payout fails |
| Direct wallet settlement | Invoice total minus route-specific execution costs (including any exchange sell or trade fees) and conversion costs you can verify in writing | Higher execution burden: chain matching, exchange conversion, and self-managed troubleshooting |
| Bank transfer | Invoice total minus all route-specific fees and FX conversion costs you can verify in writing | Cutoff timing, intermediary deductions, and amount certainty |
| Card rail | Invoice total minus percentage fee minus fixed fee minus cross-border surcharge minus FX surcharge minus expected chargeback drag | Effective cost on small invoices and post-delivery dispute reversal risk |
Headline fee is not your real fee#
For cards, use: effective card rate = % + fixed ÷ AOV. On smaller invoices, fixed fees raise the effective rate, and cross-border plus FX surcharges can add more drag.
Also model chargeback risk explicitly. A practical structure is processing, cross-border plus FX, chargebacks, then total cost. With a chargeback loss multiplier, 1.0 means order value only. >1.0 includes operational effort, fees, and penalties.
A direct on-chain transfer does not have the card-network chargeback process, but that does not remove contract disputes, fraud, freezes, or reversal risk on separate provider and fiat legs. Model those risks alongside trading, conversion, network, and cash-out costs rather than assuming a universal zero-loss crypto route.
Price both money loss and delay risk#
Track two outcomes for each route: net money loss and delay to usable cash. A slightly higher-fee route can still be the safer choice if timing is more dependable for your cashflow. Before quoting any crypto route:
- confirm the exact path in writing: asset, network, conversion step, withdrawal method, and fee ownership
- build low and high estimates for both net proceeds and time to spendable cash
- keep records: fee terms, support replies, invoice terms, transaction records, and withdrawal records
Practical rule: if a major cost line is still "varies" at quote time, treat that variability as billable risk. Add a buffer or decline crypto terms and invoice via fiat bank transfer.
If you want a deeper dive, read our 2026 Stripe, PayPal, and Wise comparison for freelancers.
Before you accept a payment rail, run your own net-to-cash math with this payment fee comparison tool.
Lock payment terms that prevent avoidable disputes#
Before you take a crypto payment, lock three things in writing: a transaction-level clause, a defined evidence pack, and a hard fallback rail. When those are explicit, avoidable payment disputes are easier to prevent and resolve.
A useful payment clause defines the asset, network, pricing moment, confirmation evidence, fees, deadlines, and incident handling. The clause operates within the contract and applicable law; it does not eliminate legal payment or dispute obligations.
Write the payment clause at the transaction level#
State the payment route in plain language and define what counts as completed payment:
- exact asset, network, token contract where applicable, destination, and required memo or tag
- receiving wallet address or approved provider account
- who pays network fees
- when payment is considered made
- who owns conversion timing risk when the invoice is fixed in fiat
- what happens if funds are sent on the wrong network
- fallback deadline, status-verification owner, and treatment of any late first transfer to prevent duplicate payment
A transaction hash alone is not proof of payment. Verify the successful transfer on the agreed network, correct token contract where applicable, destination, amount, required memo or tag, and the confirmation or finality standard in your terms. For a custodial destination, also verify provider credit and availability. Store the hash with that evidence.
Assign the risks that usually cause arguments#
Fee shortfalls and conversion timing should be assigned explicitly. If the invoice is fixed in fiat, say whether the client must cover network costs so you receive the full invoiced amount, or whether you accept the shortfall risk.
Do the same for price movement: define who bears the gap between invoice timing and conversion timing. If you cannot agree on the pricing moment, switch to bank transfer terms.
For wrong-network transfers, keep the language strict and realistic: treat them as not completed payment under the clause, and keep any recovery effort separate because it may fail.
Define the evidence pack before there is a dispute#
List the evidence in the agreement before anything goes wrong. Keep it simple and verifiable: invoice, acceptance proof, wallet transaction IDs, payment confirmations, and platform logs from the provider or marketplace.
If a provider or merchant account is part of the flow, add a pre-work checkpoint for account verification. Verification can include business documentation, identity checks, and compliance review. Unverified accounts may face limits or restrictions by business type or region.
Check marketplace policy before you move off platform#
For work sourced through a marketplace (for example, Upwork), check current platform policy before you agree to off-platform crypto terms. Use current official documentation, not old screenshots or forum assumptions.
Upwork prohibits taking payment outside its platform as circumvention unless you follow its permitted process, such as paying its conversion fee. Check the official terms applicable to the relationship before agreeing to a crypto route; a different currency does not create an exception.
Add a hard fallback#
Define a fallback deadline and owner, but resolve the first transfer’s outcome before requesting replacement payment. A pending or unknown crypto transfer can arrive later. Switch rails only after confirming that the original failed or cannot complete, or documenting how a late receipt will be credited or returned so the invoice is not paid twice.
Related reading: The Best Ways for Freelancers to Accept Payments on a Website.
Execute each payment in a strict order#
Once the terms are set, execution should be boring and repeatable. Treat each crypto payment like a checklist, not a single transfer. Use the same internal sequence every time:
- Issue the invoice.
- Confirm the destination details and network in writing.
- Run any internal pre-transfer checks you use.
- Receive the full transfer.
- Mark payment complete only after your internal confirmation and reconciliation checks are done.
- Send receipt confirmation.
- Store proof with the invoice records immediately, including the transaction record.
This matters even more as volume grows. Execution is not just sending funds; network fees, compliance checks, reconciliation, and reporting are all part of the job, and the operational load rises quickly as payouts scale. Delays, errors, and failed payments can quickly become material operational risks.
Do not confirm receipt from a screenshot or transaction hash alone. Check the actual successful transfer, destination and asset, agreed confirmation or finality threshold, provider credit where relevant, and invoice amount. Keep payment receipt separate from your later conversion and bank withdrawal.
Save records as you go: invoice details, destination confirmation, transaction ID, timestamps, relevant wallet or provider exports, and your receipt confirmation note. Keeping that evidence together supports cleaner reconciliation and helps if you later need to report digital-asset activity, including the Form 1040 or Form 1040-SR digital-asset question.
Convert and withdraw with volatility control#
The payment is not really done until the money is where you can use it. Set your conversion plan before funds arrive so market moves do not end up driving your cashflow decisions.
Set the conversion rule in advance#
For crypto payments, decide your default in writing before payment lands: convert on confirmed receipt, or hold only a pre-set amount you are willing to keep. The risk is making that call after the market moves, because that turns routine invoicing into an unplanned position.
Keep the rule practical: operating cash first, optional coin exposure second. Convert what you need for expenses promptly, and treat any holdback as a deliberate exception.
Stablecoins may reduce price swings, not cash-out steps#
Stablecoins are still digital assets, and converting them into spendable currency still requires a workable path. Before relying on that route for real obligations, run one live withdrawal on the same path and record:
- on-chain receipt confirmed
- withdrawal request submitted
- bank account credited
Use that evidence, not assumptions, to decide whether the route is dependable for deadline-based expenses.
Compare routes by consistency and evidence#
If you are choosing between payout routes, compare them by repeatable execution and records, not broad speed claims. Check:
- whether each stage is visible from receipt to bank credit
- whether exports clearly tie back to invoice and transaction details
- whether repeated tests behave consistently
- whether manual steps could delay time-sensitive payouts
Store those records with the invoice so conversion and withdrawal are easy to reconcile later.
Keep a short reserve outside the crypto path#
Do not let one delayed withdrawal block essential operating expenses. Keep a short fiat reserve so near-term fixed costs are not dependent on a same-day or first-time withdrawal path.
For U.S. workflows, this also supports cleaner reporting. Digital assets are treated as property, income from digital assets is taxable, and filers may need to report transactions and answer the digital-assets Yes or No question on returns including Form 1040 or 1040-SR.
Handle failures fraud and gray-zone support cases#
Assume at least one payment will go wrong, and decide in advance who owns what. Recovery can be harder when funds move through pseudonymous addresses, so your process should assume escalation, not easy reversal.
Assign responsibility by incident type#
Do not start with blame. Start with incident type, then route it to the right owner with complete records.
| Event type | Likely owner | First move | Evidence to collect |
|---|---|---|---|
| Sender used wrong chain or token, or different destination details than written instructions | Sender, unless your instructions were wrong | Pause further transfers and preserve transaction records | Invoice, written payment instructions, destination details shared, transaction ID or hash |
| Confirmation delay or wallet or provider status mismatch | Network or provider until clarified | Verify successful transfer, agreed finality or confirmations, and provider credit before marking paid | Transaction ID, explorer status, wallet or provider screenshots |
| Returned payout or failed fiat withdrawal | Provider or bank step | Capture exact rejection or return message before retrying | Withdrawal reference, payout status, bank return notice, account details used |
| Account hold or payout hold | Provider compliance review | Respond quickly and consistently to requested documents | Submitted KYC or source-of-funds docs, ticket ID, request timeline, invoice or client context |
| Escrow disagreement not resolved quickly | Shared gray zone (client, platform, contract terms) | Pause release steps still under your control and follow contract fallback | Contract clause, milestone acceptance proof, escrow record, client communications |
A useful distinction is error versus control. User mistakes and compliance controls are different failure modes, and controls like KYC checks, delays, limits, and convertibility constraints reduce risk but do not eliminate it.
Define escalation paths before the first invoice#
Set up a one-page escalation sheet for each provider and exchange in your payout path before you invoice. Include bookmarked login URLs, official support entry points, account identifiers, and required case-reference fields so you are not figuring this out under pressure.
Use bookmarked official login and support pages. Never disclose private keys or recovery phrases to a client, support agent, or recovery service. Treat lookalike domains and unexpected requests to connect a wallet or authorize a transaction as incident signals, and verify through an independently known channel.
Build fallback actions into delivery decisions#
When a transfer is delayed, misrouted, or disputed, preserve evidence and establish its actual status. Before invoking the fallback, prevent duplicate payment by confirming failure or agreeing how any later receipt will be accounted for. Delivery decisions should follow the contract’s verified-payment conditions rather than an unverified support promise.
Keep one reusable evidence packet per payment#
Support cases are harder to resolve when records are fragmented. Maintain one packet per payment with invoice terms, payment instructions, transaction records, status screenshots, fiat-leg return notices, and support or KYC history.
Keep tax and compliance records audit ready#
If you accept crypto, your recordkeeping has to be stronger than your memory. Keep one complete file per payment lifecycle, and separate receipt, conversion, and withdrawal as distinct events.
Record the payment at receipt, not from memory later#
For U.S. tax reporting of services paid in digital assets, record the U.S.-dollar fair market value at receipt and its valuation source. That value generally becomes the basis of the asset received; a later sale or swap can create a separate gain or loss. Confirm the accounting and tax treatment that applies in your jurisdiction.
Even small transactions can be taxable events, and volatility makes backfilling harder. If your jurisdiction uses property-style treatment (for example, the U.S. approach tied to Notice 2014-21), keep receipt and later disposal clearly separated.
Keep a practical record set for each payment lifecycle#
Do not rely on a single exchange export or wallet screen. Build a practical record set from invoice through final withdrawal. It can include:
| Record | What it captures |
|---|---|
| invoice and client communication | amount, date, chain, and token |
| wallet transaction ID and receiving address | receipt |
| receipt-day valuation record | used in bookkeeping |
| conversion records | any later sale or swap |
| fee records | network and provider fees when visible |
| withdrawal proof | when funds move to a bank or another account |
Quick check: can one folder show when income was received, when it was converted, what fees were paid, and what was finally withdrawn? If not, the file is less likely to be audit ready.
Separate income events from conversion events#
Treat receipt, conversion, and withdrawal as separate entries, even on the same day. If payment is received and immediately converted, keep separate evidence for:
- value when funds hit your wallet
- conversion amount and fees
- amount withdrawn or transferred onward
Keep income reporting separate from information-return thresholds. Under the current federal third-party settlement organization rule, Form 1099-K reporting generally requires both more than $20,000 of gross reportable payments and more than 200 transactions; payment-card reporting has no minimum threshold. Lower state thresholds or other reporting circumstances can still produce a form. Certain custodial broker sales use Form 1099-DA instead. A reporting threshold does not make service income tax-free.
Make the file structure boring and repeatable#
Use separate business and personal accounts where possible, and mirror that separation in folders. A naming format like YYYY-MM-DD_Client_Invoice#_Asset_Chain_Event keeps records sortable and reviewable under pressure.
If you accept crypto regularly, use one folder per invoice with subfolders such as 01 invoice, 02 receipt, 03 conversion, 04 withdrawal, and 05 client comms. Rules vary by country, and sometimes by state or program, so confirm treatment with a qualified tax advisor before filing. Related: the digital nomad tax guide.
Vet platform claims before trusting your cashflow#
Before you trust a platform with urgent cashflow, verify the payout rules on the primary policy pages. Forum threads can help you spot patterns, but they are not policy and may carry little weight in a dispute.
For marketplace work, read the current official payment and off-platform rules for the particular relationship and save the applicable policy with your contract. On Upwork, check its circumvention policy and permitted conversion process. Apply the same current-policy check to any other marketplace before changing payment routes.
For Ruul, Nebeus, CryptoTask, and CoinGate, ask for written answers before routing a time-sensitive invoice:
- What happens if a payout fails, is delayed, or hits a timeline exception?
- Is there any reversal or recovery path on the provider or fiat leg?
- What proof can you export for support: status history, payout ID, timestamps, CSV or PDF, and ticket log?
If support cannot answer clearly before funds move, plan for edge cases to be slow and manual.
Treat marketing terms the same way. Labels like Insured Cold Storage and smart-contract escrow only matter if they explicitly cover your exact payment path, asset, and failure point.
Check provider identity and support channels independently before funding an account. A third-party scam list can be incomplete or outdated; absence from a list is not proof of legitimacy. Treat unexplained domains, payment instructions, or requests for recovery phrases as reasons to pause and verify.
Need the full breakdown? Read Freelance Bookkeeping for Faster, Safer Client Payments.
Use a practical control checklist you can repeat on every client#
Consistency is the control. Use the same checklist on every payment so decisions, records, and reconciliation stay consistent instead of becoming ad hoc.
| Control | Detail |
|---|---|
| Record the acceptance decision | accept, accept with conditions, or decline |
| Confirm coin type and network | in the same written thread when applicable |
| State fees | who pays network and provider fees |
| Name the payout route | if a provider is involved |
| Agree a fallback | Resolve first-transfer status and any late receipt before replacement |
Before funds move, confirm payment terms in writing and resolve ambiguity early. If key terms in your agreement, such as asset, network, who covers fees, and a fallback rail, are unclear, pause and use your backup payment route.
Capture invoice, destination-verification, successful-transfer and provider-credit evidence, receipt confirmation, conversion and withdrawal records, and incident references. Mark the invoice paid according to the agreed verified-receipt rule; track subsequent conversion and bank availability separately.
Reconcile to expected net, not gross received. Check spreads, network costs, provider charges, and conversion or withdrawal fees against what you expected.
Run a short monthly review to tighten weak points. If you keep seeing the same failures, update your terms and process so duplicate-payment issues, cashflow disruption, and administrative burden are less likely. Also check whether system changes fixed one duplicate risk while introducing another.
Frequently Asked Questions
Should freelancers accept crypto payments at all?
Potentially, but treat it as a process decision, not a default. The practical setup is the key part: wallet, invoicing, and tax apps. If that setup is unclear, use stricter conditions or a simpler payment rail.
Are crypto payments safer than bank transfers for freelancer invoices?
Not automatically. Focus on whether your payment path is clear, including confirmation and processing steps you can actually verify. If you cannot verify and reconcile cleanly, risk may still be high.
Should I take Bitcoin or Ethereum instead of stablecoins?
For a fixed fiat invoice, agree the pricing source, quote validity, asset quantity, and who bears price movement and fees. Bitcoin and Ether expose you to volatility; stablecoins also carry depeg, issuer, freeze, and cash-out risks. Use a route whose receipt and conversion conditions you can verify.
How do I avoid losing money to FX spreads and hidden payout costs?
Estimate network, provider, conversion spread, trading, and withdrawal costs using a current quote for the exact route. Reconcile actual spendable proceeds against that estimate. A small test confirms the process, but does not guarantee later prices or withdrawal timing.
What records do I need for tax compliance on freelance crypto income?
Keep invoice, asset units, network and destination, successful-transfer evidence, receipt time, valuation source, fees, later conversion, and bank-withdrawal records. For U.S. service income, record dollar fair market value at receipt and track later disposals separately. Your reporting obligation does not depend on receiving an information return.
What should I do if a client sends funds on the wrong network?
Pause further transfers and preserve the transaction hash, actual asset/network, destination, and original instructions. Verify the status and use the receiving provider’s official support process. Recovery may be unavailable or limited to particular assets and networks. Do not request a replacement until the first transfer’s outcome and any late-arrival handling are resolved.
How can I compare Ruul, Nebeus, CoinGate, and CryptoTask without relying on marketing pages?
Use one checklist for all providers and test the same payment path each time. At minimum, verify how payment links are generated and how confirmation and processing appear in practice. Choose the option that gives you the clearest, repeatable operational trail for your invoicing and tax records.
Try a related tool
Researched and edited by the Gruv editorial team. Gruv builds cross-border billing, payouts, and finance-operations software for global businesses.
Sources
Includes 3 external sources outside the trusted-domain allowlist.
Educational content only. Not legal, tax, or financial advice.
Related Posts

How Freelancers Can Report Crypto on Taxes Without Guesswork
To report crypto on taxes without creating contradictions in your return, follow the same order every time: confirm your filing context, define what is reportable, then decide whether any unknowns still let you proceed or require escalation. A few terms need to stay precise:

Stripe vs PayPal vs Wise for Freelancers in 2026
Cashflow reliability matters more than brand familiarity. If money arrives later than expected, gets reduced by fees, or loses value during conversion, margin disappears even when the client technically paid on time.

Digital Nomad Taxes in 2026 With a Defensible Filing Plan
With digital nomad taxes, the first move is not optimization. It is figuring out where you may be taxable, where filings may be required, and what proof supports that position.