
Quick Answer
For ordinary Singapore-based freelance businesses, compulsory GST registration generally applies if taxable turnover exceeds S$1 million for the calendar year or is reasonably expected to exceed it in the next 12 months. The application and effective dates differ. Voluntary registration is a separate choice with eligibility and conditions. Once registered, apply 9% to standard-rated supplies, substantiate zero-rating and file and pay by the applicable deadlines.
The Pre-Threshold Stage (< S$1M): Building Your Compliance-Ready Foundation#
Before you get close to registration, put four controls in place: turnover monitoring, separate handling for tax cash, invoice readiness, and consistent revenue classification. Those basics do most of the work. They help you count taxable turnover correctly, spot issues early, and avoid a rushed cleanup later.
Build your turnover monitor first#
Your first control is a turnover monitor built around taxable turnover, not total revenue. Taxable turnover is based on taxable supplies made in Singapore. Standard-rated and zero-rated supplies count. Exempt supplies, out-of-scope supplies, and proceeds from selling capital assets do not.
Review taxable turnover throughout the year, but use the correct legal tests. Retrospective registration considers the calendar year January 1–December 31; the prospective test considers reasonably expected turnover above S$1 million in the next 12 months. A rolling monitor can help planning without replacing the calendar-year test.
Separate tax cash handling early#
Before registration, you do not collect GST as though you were registered. You can model the later pricing and cash effect. After registration, keep collected tax and estimated net GST due distinct from unrestricted operating funds.
This also lets you test pricing early. If registration starts, will you pass GST through, absorb it, or apply different pricing rules by client type? It is easier to build that habit now than to change billing and cash handling once filing obligations begin and GST returns and payment are due one month after each accounting period.
Keep invoice and record systems registration-ready#
Your recordkeeping should be easy to upgrade once registration happens. Keep invoice data and supporting records clean enough that you can review and classify each sale without guesswork.
Build retention discipline now. Once registered, GST records must be supportable for at least 5 years. If you cannot defend a classification from the invoice plus supporting documents, treat it as an exception and review it before it becomes part of your reported position.
Classify each invoice before the threshold forces it#
Classification is where small errors become bigger turnover and filing problems. Tag each invoice as you issue it, while the facts are still clear, instead of trying to reconstruct treatment later.
| Supply bucket | What it means | Counts toward taxable turnover | Keep these records |
|---|---|---|---|
| Standard-rated | Taxable supplies generally charged at GST once registered | Yes | Contract/SOW, invoice, payment evidence, delivery/performance support |
| Zero-rated | Taxable supplies charged at 0% only when conditions are met | Yes | Contract, invoice, customer belonging/location support, export or service evidence |
| Exempt | Supplies where GST is not applicable | No | Contract, invoice, internal classification note |
| Out-of-scope | Supplies outside GST Act scope | No | Agreement, invoice, counterparty/location evidence, internal rationale note |
Zero-rated treatment needs extra care. It is not automatic. For international services, you may need to determine customer belonging status first. If support is unclear, log it as an exception instead of forcing a tag.
Monthly workflow checklist#
Use one short monthly review so your classification and turnover tracking stay current.
| Task | Details |
|---|---|
| Review turnover and supported forecasts | Track calendar-year taxable turnover and next-12-month expected taxable supplies separately |
| Tag every invoice | Standard-rated, zero-rated, exempt, or out-of-scope |
| Reconcile exceptions | Including capital-asset sales and reclassified items |
| Log escalation items | Invoice number, amount, and why treatment is uncertain |
If any of the following apply, talk to a pro now:
- You have mixed local and overseas supplies and the treatment is not obvious.
- Place-of-supply treatment is unclear for part of your work.
- A platform or marketplace controls billing or invoicing flows.
- Historical invoices were tagged inconsistently.
- You may have reverse-charge or overseas-vendor-registration exposure and cannot clearly rule it out from your facts.
If you want a deeper dive, read Digital Nomad Taxes in 2026 With a Defensible Filing Plan.
| Comparison | Plain-language meaning | What it changes for you |
|---|---|---|
| Mandatory vs voluntary registration | Mandatory means you crossed the current legal trigger; voluntary means you register below it. | Mandatory removes choice; voluntary is a commercial and admin choice. |
| B2B vs non-registered clients | GST-registered business clients may be less sensitive to GST than non-registered clients. | The same pre-tax fee can land very differently by client type. |
| GST vs income tax | GST is collected and remitted; income tax applies to net trade income after allowable business expenses. | Treat GST cash separately from revenue and profit planning. |
Mandatory registration dates and a worked pricing comparison#
| Ordinary trigger | Application | Effective date |
|---|---|---|
| Calendar-year taxable turnover above S$1 million | January 1–30 of the following year | Generally March 1 of the following year |
| Reasonably certain next 12-month taxable turnover above S$1 million; liability from July 1, 2025 | Within 30 days of forecast date | Generally two months from forecast date |
These normal dates assume no applicable exception. The prospective test needs supporting evidence, such as signed work, rather than speculative sales targets. A sole proprietor considers the relevant taxable turnover of their businesses together; overseas vendor registration and reverse charge have separate rules.
Assume an invented S$10,000 standard-rated service and eligible input GST of S$180 under the ordinary method. If the agreed fee is GST-exclusive and adding tax is permitted, output GST at 9% is S$900, the client pays S$10,900, and net GST before other adjustments is 900 − 180 = S$720. If the contract instead fixes a GST-inclusive total of S$10,000, GST within it is 10,000 × 9/109 = S$825.69, leaving a pre-tax fee of S$9,174.31. Registration does not automatically authorize charging S$10,900.
For a consultancy service supplied contractually to an overseas business, assess the actual Section 21(3)(k) conditions and direct beneficiaries. A Singapore non-GST-registered direct beneficiary or a relevant Singapore-property connection may change treatment. Keep customer and service facts, not just a foreign address. This conditional example does not certify a particular engagement.
The Threshold-Approach Stage: The Strategic Decision to Register#
First determine whether registration is compulsory and record the required application and effective dates. Only if it is not compulsory should eligibility, client mix and recoverable input tax guide a voluntary choice. Price sensitivity or an incomplete admin setup cannot postpone mandatory duties.
For a voluntary choice, compare eligible recoverable input tax with administration and client pricing over the required period. A business client may be eligible to recover GST, but company size is not proof. Existing fixed prices may leave you absorbing tax unless the contract permits an addition or the parties agree.
Make the call from client and pricing reality#
Start with how clients actually buy, approve, and pay. That usually tells you more than headline revenue.
| Client profile | Can client recover GST? | Your pricing flexibility | Voluntary considerations |
|---|---|---|---|
| Larger business client with finance/procurement review | Do not assume. Confirm with the client contact or finance team. | Often higher when contracts state fees before tax or allow tax to be added on invoice | Consider early registration if this is most of your book and your contracts let you pass through tax at the current GST rate without margin damage |
| Small business client with informal buying process | Unknown until confirmed | Mixed; tax add-ons can trigger renegotiation | Compare eligible input-tax recovery and administration with pricing effects; do not delay if registration is compulsory |
| Individual customer or founder paying personally | Do not assume recovery | Usually low; final price sensitivity is higher | Compare a tax-inclusive price with a permitted price increase; mandatory dates still apply |
| Overseas client or platform-routed work | Recovery may not be the main question; treatment may need review | Depends on contract terms and how the supply is treated | Get advice before using this segment to justify early registration |
This is where commercial logic and tax treatment meet. Once you know who is buying and how pricing works, you can test whether early registration helps or just adds friction.
Run the decision in order#
Set the mandatory dates first. For an eligible voluntary application, compare the following commercial factors and imposed conditions.
| Step | Action | Details |
|---|---|---|
| 1 | Classify revenue by client type and payment context | Review the related contract and invoice terms for each bucket |
| 2 | Estimate potential tax-cost impact | From your actual business costs with your bookkeeper or adviser |
| 3 | Estimate admin load realistically | Invoice controls, record quality, reconciliations, and filing workflow |
| 4 | Factor in personal liability exposure | If you operate as, or are considering, a sole proprietorship |
| 5 | Pick a default path now | If voluntary, compare options and conditions, including the two-year commitment. If compulsory, apply by the required date regardless of client mix. |
Readiness checklist before you register#
Registration is easier when your records already behave like those of a registered business, even if you have not filed yet.
- Bookkeeping can separate relevant sales categories and business costs without heavy manual cleanup.
- Invoice controls are consistent and can be updated quickly across templates and workflows.
- Cash buffer planning is in place so tax cash is not absorbed into operating spend.
- Confirm the actual business identity and documents IRAS requires for your form of business; a sole proprietor does not use a company constitution or resident-director checklist.
- New voluntary GST applicants from April 1, 2026 must meet the applicable GST InvoiceNow requirement, subject to exclusions. Assess onboarding and invoice-data submission; a generic PDF invoice generator alone does not satisfy it.
Talk to a pro before you decide if you have mixed local and overseas supplies or unclear place-of-supply treatment. Do the same if revenue swings sharply or contracts lock in tax-inclusive pricing.
Charge applicable GST from the effective registration date, not from whichever notice date is commercially convenient. Check the actual pricing terms and communicate a lawful change clearly. Obtain agreement where needed to change a tax-inclusive price; do not silently add tax beyond the contract.
An illustrative invoice can help compare pricing. For a real invoice, meet IRAS's requirements and, where applicable, InvoiceNow duties rather than treating any generated PDF as compliance.
The Post-Registration Stage: Mastering Operational Excellence#
Once you are registered, the hard part is no longer deciding whether to register. It is operational control. Your goal is to make each reporting cycle predictable, documented, and easy to review.
Problems at this stage usually come from last-minute cleanup: missing records, inconsistent invoices, unclear adjustments, and transactions entered without enough support. The practical fix is a repeatable cycle with a clear owner for each step, even if that owner is you.
If your setup still has gaps, prioritize the basics: a business account, clear tax-rule understanding, required licences, and digital tools.
Set your source of truth before you touch the return#
Start with one source of truth for each record type instead of splitting records across random folders, inboxes, and screenshots. For most freelancers, that means your business bank feed, issued invoices, supplier bills and receipts, and bookkeeping file.
If your legal name, address, or entity details change, update the master record once. Then carry it through invoices and payment records so you are not reconciling mismatched identities later.
Treat the bank feed as a checkpoint, not your accounting system. Reconcile each bank movement to an invoice, expense, transfer, payroll item, or owner draw before preparing filing materials, and confirm the current filing form and process with IRAS. If you cannot match a transaction quickly, move it to an exception queue instead of guessing the treatment.
Investigate unmatched or unusual transactions promptly and keep the actual known amounts accurate. A missing internal note is not a grace period for filing; seek help on material treatment uncertainties and use the required correction or extension process where available.
Use one invoice template and review it like a compliance document#
Use templates suited to the actual supply and recipient. A registered supplier generally issues a tax invoice for a standard-rated supply to a GST-registered customer, within 30 days of the time of supply. It is not required for every zero-rated or exempt supply or every non-registered customer.
A standard tax invoice includes the required supplier identity and GST registration number, date and identifying number, recipient details, supply description, amounts, GST rate and tax. Check the required format for the actual situation; a simplified tax invoice can be used where the GST-inclusive amount does not exceed S$1,000.
| Template field to review | Why it matters | Common error | Quick self-check |
|---|---|---|---|
| Business name and registration details (verify against current rules) | Helps connect the invoice to the correct registered business | Old trading name, wrong entity name, or missing registration detail after a business update | Does this match your current business record and template exactly? |
| Invoice number and invoice date | Helps with sequencing, period matching, and audit trail | Duplicate numbering, missing dates, or backdating | Can you trace this number in sequence without gaps or repeats? |
| Customer identity and service description | Helps show who bought what and why it was billed | Vague descriptions with no project context | Would a third party understand the service from this invoice alone? |
| Amount before tax, tax amount, total amount | Helps with accurate reporting and dispute prevention | Single blended totals or manual math errors | Do line items add up cleanly from pre-tax amount to total? |
| Tax rate shown on the invoice (verify current rate) | Helps keep output tax reporting consistent | Outdated rate or inconsistent manual entry | Does the template apply the current GST rate consistently on taxable invoices? |
After any template change, send yourself a test invoice and review the final PDF, not just the draft screen.
Run a repeatable close cycle for every filing period#
Use the assigned accounting period, generally quarterly, and its actual dates. Returns and payment are due one month after period-end. Under an approved GST GIRO plan, the deduction is on the 15th of the following month after the payment due date; keep the account funded and verify the acknowledgement.
| Step | Action | Details |
|---|---|---|
| Reconcile records | Match bank movements to invoices, bills, and receipts | Remove duplicates and move unclear transactions to the exception queue |
| Validate treatment | Review sales and expense coding for unusual items | Confirm consistency with your current rules and adviser guidance |
| Prepare the return | Generate draft figures from your books | Compare them against expected activity for the period |
| Final review and submit | Assign a final reviewer | If you are solo, still treat this as a separate pause-and-check step before submission |
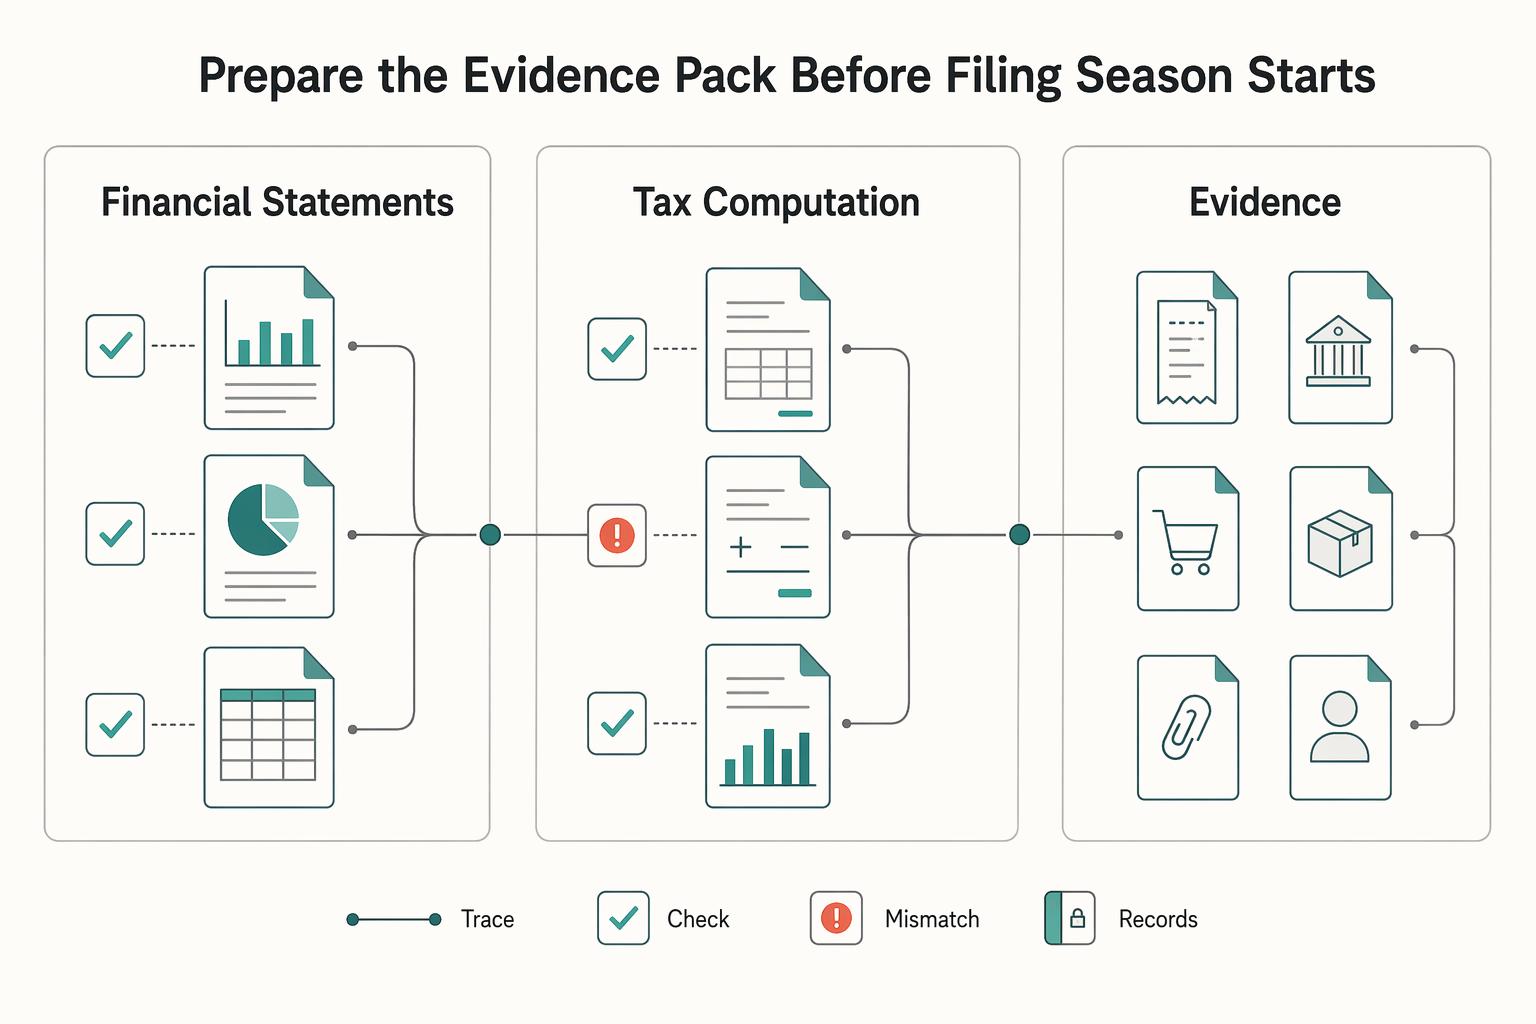
| Confirm payment and archive evidence | Confirm the payment amount and status | Archive the filed return, payment confirmation, working papers, and support documents in one period folder |
Trace a discrepancy to its sources and correct the entry. Resolve material uncertainty promptly, but do not assume an internal validation pause suspends the return or payment deadline.
Make compliance visible, but keep the claim modest#
Use registration details as a trust signal, not a promise of outcomes. Put them where finance and procurement teams can find them quickly: invoice templates, proposal templates for larger clients, and your website legal or contact page when relevant.
Mention compliance when buyers ask for supplier tax or invoicing details during onboarding. Otherwise, let routine transactions follow your standard process. Review unusual transactions, especially those with cross-border elements, unusual adjustments, or contract language that changes how amounts are stated, before billing. Related: A Guide to Singapore's Corporate Tax System for Foreign Entrepreneurs.
From Obligation to Advantage#
Build the controls early and apply both compulsory registration tests. If liable, follow the application and effective dates regardless of client preferences or pricing convenience. Below the compulsory threshold, assess eligible voluntary registration using real client, pricing and administration facts. After registration, follow the assigned return cycle.
Setup#
Track calendar-year taxable turnover and supported next-12-month forecasts separately. A business can trigger the prospective test before calendar year-end; the retrospective test is not a generic rolling past-12-month calculation.
Record the trigger date and application deadline before commercial discussions. A prospective application is due within 30 days of the qualifying forecast. Retrospective calendar-year liability normally requires applying January 1–30 of the following year, with registration effective March 1.
Strategy#
Commercial timing matters only for eligible voluntary registration below the compulsory threshold. GST-registered business clients may tolerate standard-rated pricing differently from individual buyers, but that does not change liability under the compulsory tests. Before opting in, compare pricing paths, input-tax eligibility, required administration and the generally two-year commitment. Keep the decision note with your records.
| Area | Compliance-only approach | Advantage approach |
|---|---|---|
| Threshold monitoring | Check only when revenue feels close | Track calendar-year turnover and next-12-month forecasts separately with dated support |
| Registration timing | Register too early or too late based on guesswork | Apply mandatory dates first; assess voluntary economics only where there is a choice |
| Post-registration reporting | Scramble at quarter end | Use the assigned period and its return/payment dates |
Scale#
Once registered, use the assigned accounting period and keep accurate records for at least five years. Tax reporting can follow time-of-supply rules rather than bank-receipt timing. Eligible input-tax claims require their own support and conditions.
The payoff is practical: a steadier filing rhythm and clearer readiness when larger clients ask for consistent billing and tax process discipline.
Next steps:
- Confirm current IRAS rules for threshold tests, GST rate, filing process, and deadlines.
- Tighten your turnover tracker and attach supporting records.
- Use a consistent invoice workflow and reconcile each assigned GST accounting period.
Get help for material service or cross-border uncertainties without treating that as permission to miss an invoice, return or tax deadline. Foreign registration, reverse charge and platform arrangements can require separate analysis from this ordinary domestic-business guide.
If you want a cleaner operating setup for cross-border client billing and payout workflows with traceable records where supported, review Gruv for freelancers.
Frequently Asked Questions
What is the registration threshold, and when do you need to act?
The ordinary tests are taxable turnover above S$1 million for the calendar year, or a reasonably certain forecast above S$1 million over the next 12 months. Application and effective dates differ between these tests. Monitor both and act on the relevant trigger; the table above gives the normal dates.
Should you register voluntarily?
Eligible voluntary registration can support input-tax recovery subject to conditions, but introduces GST responsibilities and generally a two-year registration commitment. Assess client pricing, actual eligible costs, administration and applicable InvoiceNow onboarding. It is not an option to delay a compulsory application.
How do you create a compliant invoice?
Use the required document for the actual supply and recipient, with your GST registration number and accurate amounts. A standard tax invoice to a GST-registered recipient generally must be issued within 30 days of time of supply. Check simplified-invoice eligibility and any InvoiceNow duties; a locked template alone is not compliance.
What happens if you file or pay late?
Identify whether the issue is a late return, unpaid tax or an incorrect filing, and use the appropriate IRAS process promptly. They can have different consequences. An internal incomplete checklist or unsettled treatment question does not automatically extend a statutory deadline.
Are services to overseas clients subject to GST?
International services can be zero-rated only when the applicable conditions are met, and those taxable zero-rated supplies count toward the ordinary taxable-turnover test. For qualifying consultancy, check the overseas contractual customer, direct beneficiaries, business capacity and exclusions such as Singapore land or goods. An overseas invoice address alone is insufficient.
How is GST different from income tax?
Keep them separate in your records and decisions. GST is a consumption tax on supplies, while income tax is assessed on net trade income after allowable business expenses. If you are allocating shared personal and business costs, get advice before posting entries.
How often do you file, and what should you verify each time?
Use your assigned period, generally quarterly; file and pay one month after period-end, subject to the applicable payment arrangement. Reconcile invoices, input-tax support and adjustments, not only bank deposits. Follow the actual deadline while resolving issues through the appropriate process.
Watch
GST Thresholds and Filing for Singapore Freelancers
Try a related tool
Researched and edited by the Gruv editorial team. Gruv builds cross-border billing, payouts, and finance-operations software for global businesses.
Sources
Educational content only. Not legal, tax, or financial advice.
Related Posts

Digital Nomad Taxes in 2026 With a Defensible Filing Plan
With digital nomad taxes, the first move is not optimization. It is figuring out where you may be taxable, where filings may be required, and what proof supports that position.
Singapore Corporate Tax for Foreign Entrepreneurs Without Filing Surprises
Delays often come from mismatches between entity records, tax timing, and filing prep, not just the 17% rate. Start in this order: confirm whether your setup is treated as a company for income tax, map the correct Year of Assessment (YA), then verify core records before estimating anything.

The Freelance Payment Penalty: A Modeled Audit of Platform Fees, FX Spreads, and Payout Delays
The money rarely disappears through a single, easy-to-spot fee. The real loss is stacked. A marketplace takes its commission, a processor adds a charge for international cards, a bank or payment company converts the currency at a spread, a platform holds the funds before release, and a wire sheds a little to intermediaries on the way in. Each layer looks defensible on its own, but the worker feels the combined result as a smaller deposit and a later payday.